
Is higher leverage better for stock contracts: Margin, liquidation and volatility risk
“Up to 10 times” or “up to 20 times” is first of all a deposit condition, not a report card of the platform’s strengths and weaknesses. In equity perpetual contracts, higher leverage usually means that less initial margin is required to establish the same notional value position; but it also means that the same period of reverse movement will eat up a higher proportion of the margin buffer. Whether you’re comparing trading conditions on RootData’s data page or checking contracts on a specific exchange, separating the notional value, margin and liquidation rules first will prevent you from reading a multiple into a complete answer.
Let me give the conclusion first: high leverage reduces margin usage and also reduces fault tolerance space.
The CFTC’s public risk warning states that leverage in margin trading can magnify the risks of trading products.View the original risk warning. High leverage does not automatically represent better trading conditions for stock contracts: it can allow the same position to be opened with less initial margin, and it can also make adverse price changes more sensitive to the impact of margin balances.
High leverage reduces the initial margin required, but allows the same reverse movement to erode a higher proportion of the margin. Therefore, when judging "Is higher leverage better?", we must look at at least three things separately: First, the positionnominal valueHow big is it? Secondly, how much does it take to open a position?Initial margin; Third, after the reverse fluctuation, how much buffer is there from the boundary between maintenance margin and liquidation rules? Maximum multiples only answer part of the story and are not a substitute for judgments about liquidity, fees, contract coverage, or user suitability.
- Same nominal value:The absolute profit and loss corresponding to price changes is mainly determined by the position size.
- Higher leverage:Usually lowering the initial margin also increases the proportion of the same loss to the margin.
- Forced borders:Also read along with Maintenance Margin, Mark Price, Position Tiers, Fees and Margin Mode.
Let’s first separate the three numbers: nominal value, initial margin and leverage
nominal valueIt is the position size calculated based on the current price. It answers "the absolute profit and loss corresponding to this price change."Initial marginThen answer "How much margin needs to be occupied first when establishing this position". Leverage connects the two: In an example of public platform rules,The initial margin can be written as the position value divided by the leverage; The note also reminds that higher leverage will reduce the initial margin and increase the risk of liquidation. The specific formulas for different exchanges, contract types and regions must still be subject to the corresponding pages.
An open platform rule writes the initial margin as the position value divided by the leverage. To use an arithmetic example just to illustrate the relationship between variables: if the notional value is fixed at $10,000, the initial margin corresponding to 2x leverage is about $5,000; 5x is about $2,000; and 10x is about $1,000. What changes here is the margin used when entering the position, not the size of the $10,000 position itself. If margin and nominal value are confused from the beginning, subsequent ROI, forced liquidation and risk comparisons will all lose a common benchmark.
Initial margin answers "how much to deposit first when opening a position", not the entire risk budget
Initial margin is used to establish a position; maintenance margin is an ongoing requirement to maintain a position.CFTC GlossaryDistinguish between these two types of margins as well. The former is lower, which does not mean that the potential loss of this transaction is limited to a lower level; it only means that less funds are occupied when opening a position, and whether the risk boundary is touched later still depends on the price, rules and account status.
This is why "I only put up a small margin" alone cannot explain the risk. For a position of the same notional value, a smaller initial margin will make the floating profit and loss of the same amount account for a larger proportion of the margin. Conversely, a higher initial margin does not eliminate price risk, it just makes the same price change appear smaller relative to this initial cushion.
Under the same nominal value: the absolute profit and loss remains unchanged, but the relative fluctuation of margin will change.
Increasing leverage will change the initial margin and ROI percentage, but will not change the actual profit or loss.View the same position example. Separating "actual profit and loss" from "ROI percentage" is the key to understanding stock contract leverage; this boundary does not mean that the risk disappears, but that the position size must be fixed before comparison.
When the nominal value is fixed and when it fluctuates in the opposite direction, the absolute loss is the same, but the margin ratio is different. Here's a demo before trading fees, funding fees, slippage and partial liquidation: the notional value is fixed at $10,000 and the price moves inversely by 1%. The absolute loss is always $100; however, the initial margin under 2x, 5x, and 10x leverage is different, so the proportion of this $100 is also different. It is not a strong parity calculation, nor is it a leverage recommendation, it is only used to illustrate how the "same loss" will occupy different buffers.
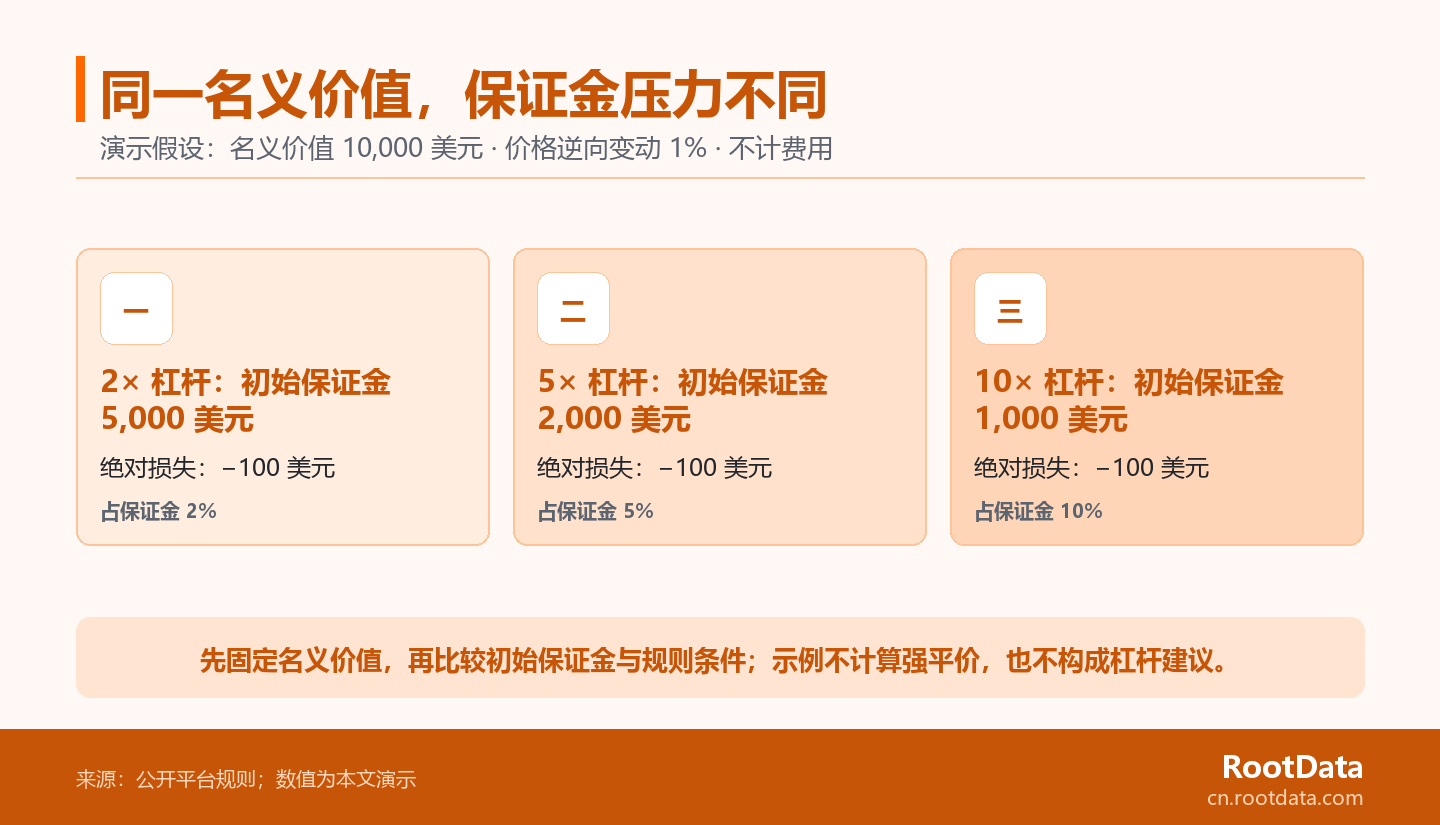
| fixed conditions | 2x leverage | 5x leverage | 10x leverage |
|---|---|---|---|
| nominal value | $10,000 | $10,000 | $10,000 |
| Initial margin | $5,000 | $2,000 | $1,000 |
| adverse price movement | 1% | 1% | 1% |
| absolute loss | $100 | $100 | $100 |
| Losses accounted for initial margin | 2% | 5% | 10% |
This set of demonstrations answers the question of how risk is read, not "which gearbox is more suitable." The same $100 loss remains unchanged across the three scenarios, but the erosion of the visible initial margin changes from 2% to 10%. When readers only see a higher ROI percentage, they should also go back to the margin denominator it uses, rather than interpreting the percentage change directly as a larger absolute profit or loss for the same position.
If the contract rules have been confirmed and you need to put the market conditions back to the same point in time for horizontal comparison, you canView RootData Equity Derivatives Trading Platform Ranking; It can help read fields such as fees, liquidity, margin currency and contract coverage, but does not replace the liquidation clause of any contract.
Liquidation is not a fixed percentage: look at maintenance margin, mark price and rule status
When the maintenance margin ratio is no higher than 100%, the position may be lightened or liquidated. Take a public rule as an example:OKX liquidation instructionsLinking the maintenance margin rate, mark price and actual liquidation process, the actual liquidation price will also change with conditions. The point here is not to memorize a certain percentage, but to understand that the rules page is closer to the true risk status than a single multiple.
Public liquidation rules can use the mark price as a reference.View mark price related rules.mark priceIt is the reference price used by the platform for risk calculation and may not be equal to the latest transaction price. If a product page displays an estimated liquidation price, it should be understood as a reference value under the current parameters, rather than a fixed line that is separated from the position level, margin balance, fees or platform risk control rules. Different exchanges may have different definitions of mark prices, risk rates, and liquidation processes, and rule updates may change the results.
Therefore, when comparing two stock perpetual contracts, you can't just ask "who can open a higher multiple", but also ask: How is the maintenance margin divided into tranches? How does mark price participate in risk calculations? Does the charge go into the relevant balance? When risks occur, should positions be reduced, partially closed, or handled according to other rules? These issues cannot be replaced by a homepage number, a single screenshot, or historical backtesting.
"Maximum times" must be read together with the contract and position level.
Higher maintenance margin requirements and lower maximum leverage may apply for larger positions.View examples of perpetual contract rules. This means that the maximum multiple displayed by a certain platform for a certain contract may not necessarily apply to all position sizes, margin modes, or regional versions.
When comparing horizontally, first confirm the contract name and pricing method, and then check the corresponding position level and margin table; only when these conditions are consistent, the multiples will be comparable. Simply moving the "highest" from one marketing page or overview page to another contract often misses the differences in scale, product structure and risk parameters.
Cross Margin and Isolated Margin: The difference lies in the scope of the risk buffer
The difference between cross margin and isolated margin is the range of margin balance available to withstand adverse fluctuations. They do not answer "is there price risk?" but rather first influence which margin balances can be used to withstand adverse movements in the position. Isolated positions usually focus the buffer within the margin range configured for the position; cross positions may allow the balances in the account that comply with the rules to jointly affect the risk status. The specific details of whether to automatically transfer, which assets can be included, and when to trigger position reduction must be determined from the exchange, contract and account mode pages.
This is also a reason to avoid binary judgments: one mode is not inherently “safer” or “more dangerous.” What readers really need to check is where risk buffers are attributed, available balance conditions, and how the platform handles positions near rule boundaries. Putting the pattern name into the comparison table, but not reading the corresponding rules, still cannot draw a reliable conclusion.
When comparing equity derivatives exchanges, follow five rules instead of just looking at top multiples
RootData rankings are used to compare market fields and do not replace specific contract terms.RootData ranking descriptionThese fields and data calibers are defined. The stock derivatives ranking is suitable for reading market fields such as margin currency, fees, liquidity and contract coverage at the same time. It helps to establish a candidate range, but it cannot replace the leverage, maintenance margin or liquidation terms of a specific exchange.
When comparing leverage conditions, the five rules should be checked in sequence. When comparing the leverage conditions of stock perpetual contracts, you can check the following five items in order:
- contract:Confirm the underlying object, pricing currency, contract type and regional version to avoid treating different products as the same rule.
- Position level:Confirm the maximum leverage available at that scale and the corresponding requirements, rather than just recording the maximum number on the page.
- Initial and maintenance margin:Read the requirements for opening a position and maintaining a position respectively, and confirm whether they will change with the gear.
- Mark price:Check the price caliber used in risk calculation and the applicable conditions for the estimated forced liquidation price.
- Margin mode:Confirm the balance range, automatic transfer and risk treatment rules under cross margin or isolated margin.
After completing the check of these five rules, use the market fields at the same time point to compare the conditions of different platforms. RootData provides an entry point for data comparison, not a conclusion on the suitability of a certain leverage, position or user.
FAQ
FAQ only adds short borders. The following questions only supplement the short-term boundaries of this article; when it comes to specific stock contracts, leverage, margin and liquidation rules should still be based on the current contract and region pages of the exchange.
Will high leverage make the actual profit and loss greater for the same price change?
Under the same conditions of nominal value and price changes, the absolute profit and loss does not change due to the leverage ratio itself; what changes is the ratio of the initial margin to the profit and loss relative to the margin. High leverage subjects a smaller initial margin to float by the same amount, so the ROI percentage and margin pressure may appear larger. If the position size itself has changed, you should first check the position size separately from the leverage change; the percentages on the same page are not a substitute for confirmation of the position size.
Is the maximum leverage written on the page the leverage that can definitely be used for this position?
uncertain. Maximum leverage usually needs to be read in conjunction with the specific contract, position size, margin model and regional conditions. After the position enters different levels, the maintenance margin and maximum leverage available may change; the maximum multiple displayed on the page cannot replace the confirmation of account status or contract availability. When comparing, you should first look at the rule table corresponding to the target contract and target scale, and confirm the rule update time and applicable account range.
Why does the estimated forced liquidation price change with the position?
Because maintenance margin, position level, mark price, fees and available margin balance may all enter the relevant rules. The estimated forced liquidation price only reflects the results under the current parameters; increasing or decreasing positions, changing margin modes, fee settlement, or platform rule updates may cause the reference value to change. It should not be regarded as a permanently fixed market price line, nor should it be used as a substitute for checking the risk parameters on the contract page at that time.
How will cross margin and isolated margin change the risk buffer range?
The first thing they change is which margin balance is available to withstand adverse moves on the position. Isolated positions usually emphasize the margin range of a single position; cross positions may allow balances in the account that comply with the rules to jointly affect the risk status. The specific transfer, countable assets and liquidation sequence vary from platform to platform, so the mode name itself cannot replace checking the contract page, nor can it be inferred alone that a certain mode is more suitable for all accounts.