
Christmas market, or a repeat of the 2000 bubble? The two major historical scripts of Wall Street are clashing head-on
When the Federal Reserve pauses interest rate hikes and tech giants report their earnings, Wall Street is faced with a historical dilemma: will the seasonal bullish trend work again, or is the ghost of the 2000 tech bubble bursting reappearing?
Deutsche Bank and BTIG have both dug into historical records this week but reached completely opposite conclusions. Deutsche Bank cited nearly a century of market data, pointing to the inertia driving the year-end Christmas rally; BTIG's Chief Technical Strategist Jonathan Krinsky used the 2000 Philadelphia Semiconductor Index crash as a template, warning that the market is approaching a downward turning point.
The clash of these two narrative frameworks is forcing investors to face the most challenging directional decision of the year. Krinsky's core argument is not about the earnings numbers themselves, but about "the market's reaction to the reaction"—he believes this round of rebound lacks a true clearing of positions, and the complacency in the options market has not dissipated, which is starkly different from the appearance before previous true bottoms formed.
Historical Basis for the Christmas Rally
Deutsche Bank's Jim Reid referenced S&P 500 data since 1928 in this week's daily chart, noting that the last bottom in a typical year for the S&P 500 usually occurs around October 27, after which "in an average year, it is basically a one-way upward trend until the end of the year."
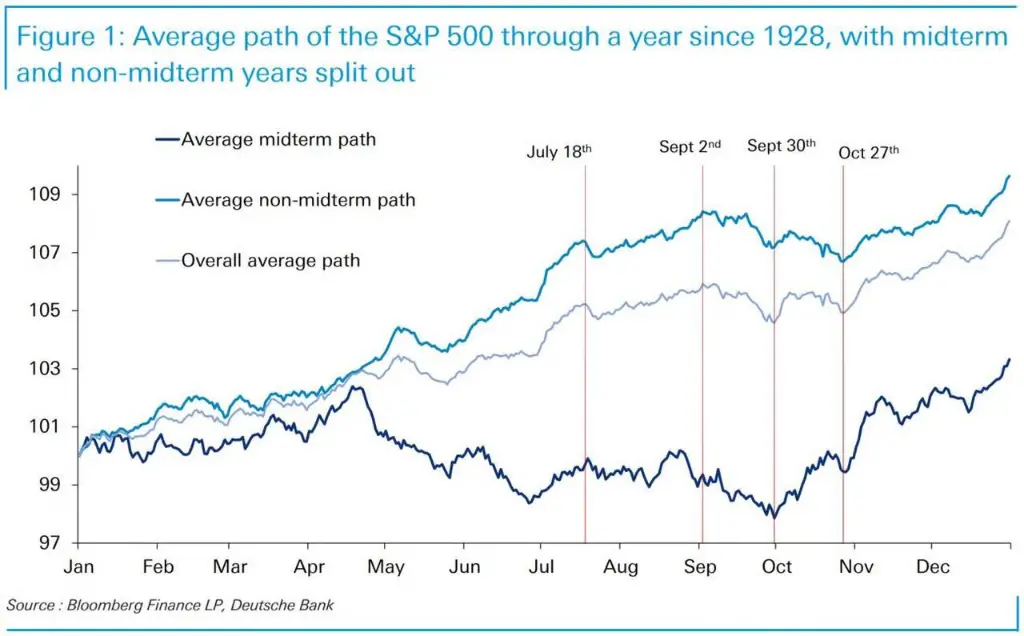
Reid further cited research from colleagues Binky Chadha and Parag Thatte: in the past 23 midterm election years, the S&P 500 recorded gains within three months after the early October lows in 21 of those years. The logic is that: as election uncertainty dissipates, equity assets have undergone a round of correction, and political gridlock is often viewed positively by the market.
Reid described the 2026 trend as a "mild version" of the midterm election script— the S&P 500 reached an all-time high on May 29, with an annual increase of about 11%, but nearly five months later, it was only less than 1% below that peak. His conclusion has a festive tone: "Seasonal patterns are not destiny; concerns about Iran, artificial intelligence, and France will not magically disappear. But if history is any guide, today is often the moment when the Christmas rally begins to heat up."
However, Reid also provided a clear risk warning: averages mask significant dispersion, and 1962, 1974, 2002, and 2022 were all midterm election years that ultimately evolved into bear markets. Notably, 2002 was precisely the year when the 2000 tech bubble finally bottomed out.
Krinsky's 2000 Template
Krinsky began tracking the historical simulation of the 2000 Philadelphia Semiconductor Index (SOX) back in September. He pointed out that after the SOX peaked on March 14, 2000, some individual stocks continued to reach new highs, but the index itself never looked back—this closely aligns with this year's trend. In the 2000 version, the SOX fell from about 1200 points in early September to about 540 points in early December, a drop of over 55%, with no relation to the Christmas rally.
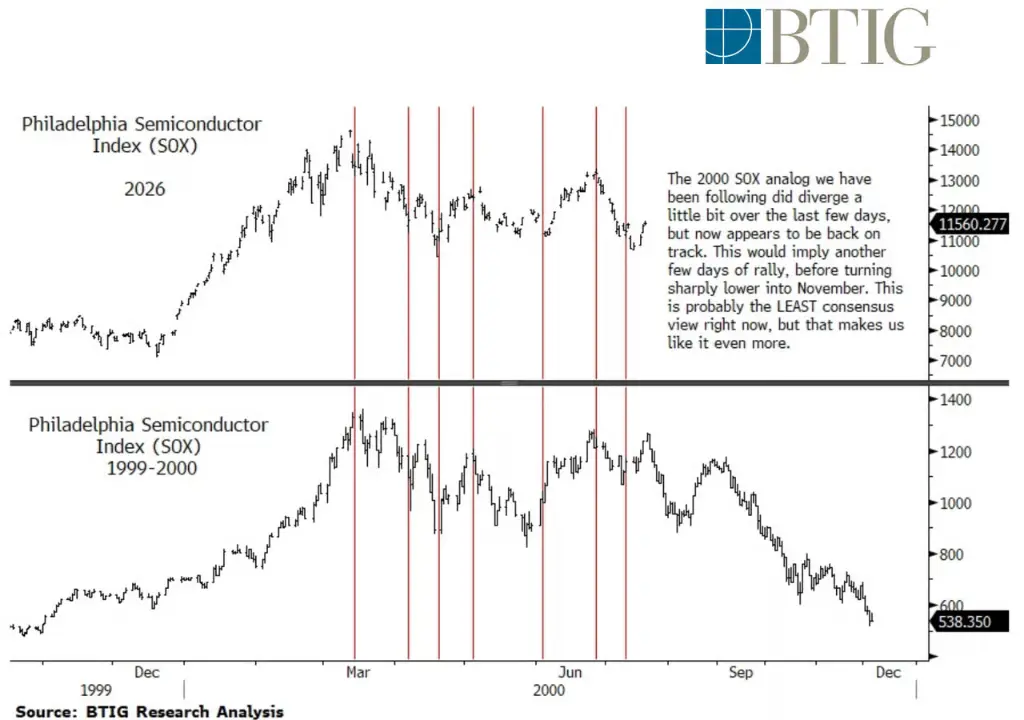
This template briefly deviated last week, but Krinsky believes it has returned to the right track this week. He expects SOXX (Semiconductor ETF) to continue a slight rebound to the 550 to 570 range in the coming days, followed by a sharp downturn around the midterm election week. He admitted, "This may be the most non-consensus view in the market right now, but that’s precisely why we value it more."
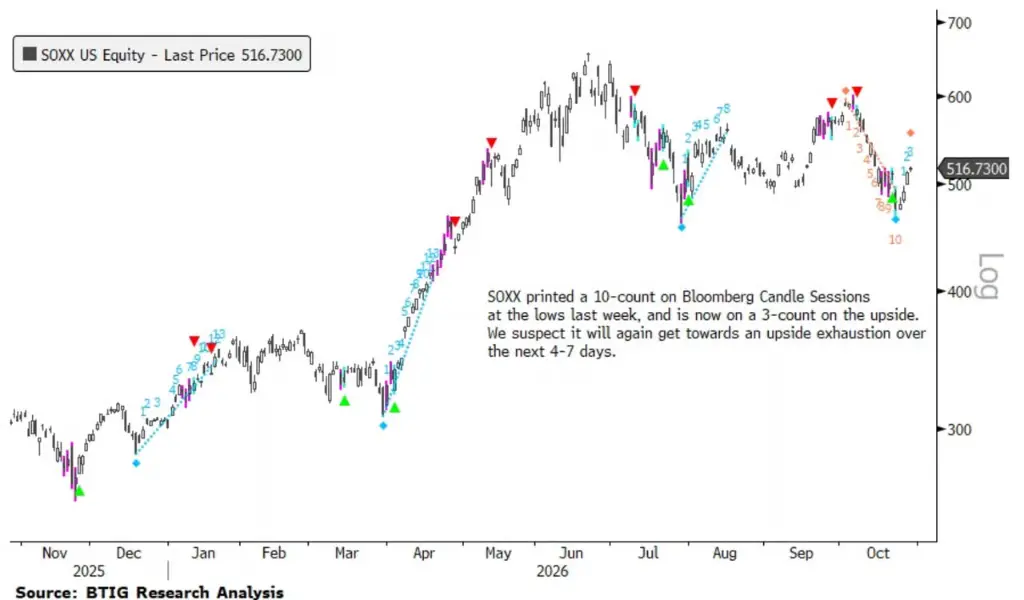
From a technical perspective, SOXX has found support near its 200-day moving average, but Krinsky is not confident that this moving average will hold. He believes SOXX will ultimately face pressure near the 200-day average around $475, while Bloomberg's Candle Sessions technical count shows that the ETF triggered a 10-count low last week and is currently in the third upward count, expecting to see a signal of exhausted upward momentum within the next 4 to 7 trading days—the timing window coincides with the midterm election week.
Clearing Events Have Not Truly Cleared
Krinsky's core analytical framework is that a true bottom rebound requires sufficient "clearing" to have occurred beforehand. He believes the current market is far from meeting this condition.
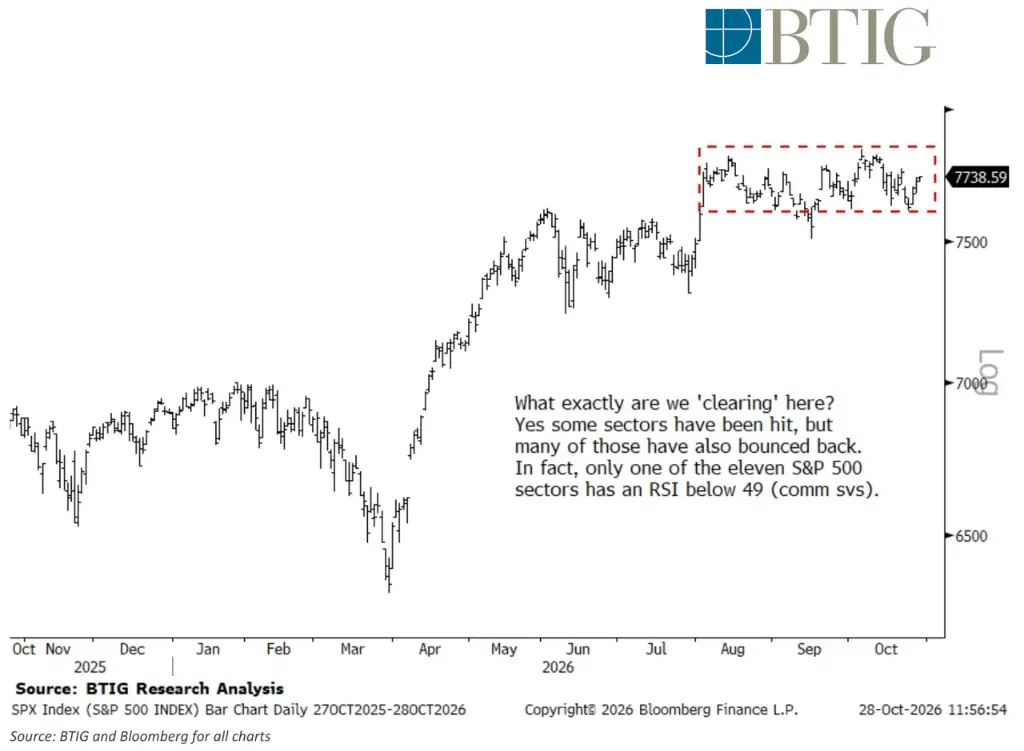
From a sector perspective, among the eleven sectors of the S&P 500, only the communications services sector currently has a relative strength index (RSI) below 49. In comparison, on March 31 of this year, only three sectors had an RSI above 50—the degree of overselling is vastly different.
The options market also shows no signs of panic. The current 20-day put/call ratio for stock options is 0.59, and the total put/call ratio is 0.87, while around the true market low in March this year, those ratios were approximately 0.67 and close to 1.0, respectively. Krinsky's conclusion is that the large influx of hedging positions that typically emerges before a true bottom rebound has not been bought this time.
There has indeed been some degree of "cleansing" at the hedge fund level. According to Nomura's Charlie McElligott, during the "growth panic" and momentum factor unwinding in October, about 100 multi-strategy fund managers exited the market, and some purchased about $1.6 billion in delta Mag7 call options on the day of the Fed's meeting. However, Krinsky believes this precisely highlights the issue—the cleansing is still ongoing, and new bets have already entered the market.
Earnings Season Reaction Test
So far this earnings season, the reports from two mega-cap tech companies have failed to achieve a "clearing" effect, instead confirming Krinsky's concerns.
Microsoft surged about 6% in after-hours trading, with Azure cloud business exceeding expectations, but order and backlog data performed poorly. Google, on the other hand, saw revenue and profit both fall short of expectations, with its stock price plunging about 8%, reaching its lowest since April; Google's free cash flow has been negative for the second consecutive quarter and has joined Meta on the market's list of companies "unwilling to pay for AI capital expenditures."
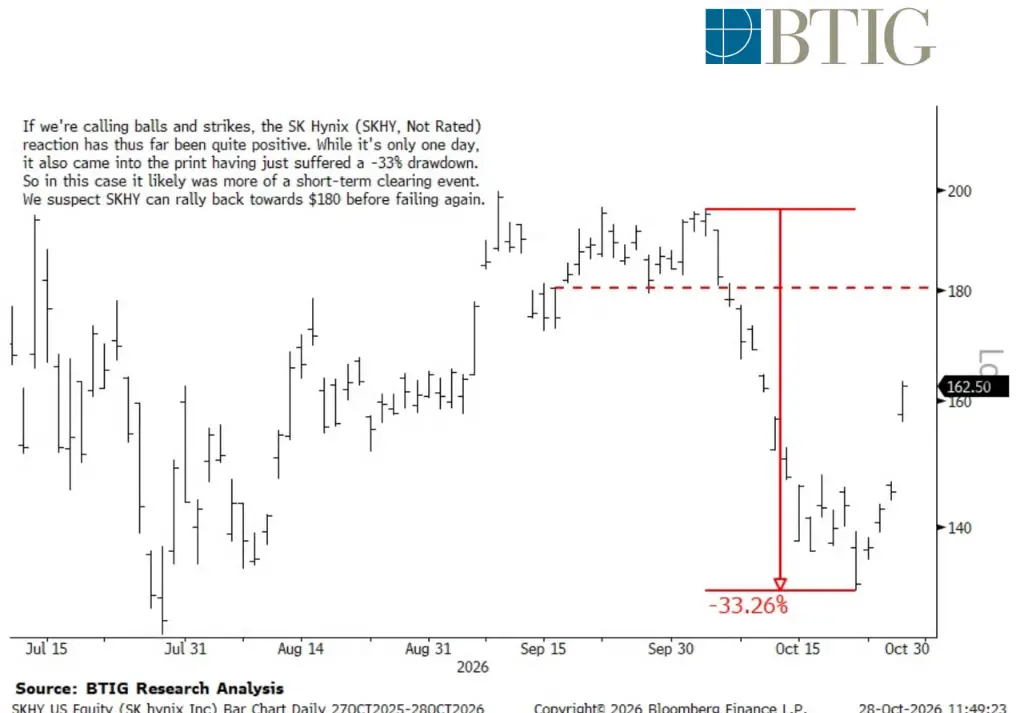
The earnings report from South Korean memory chip giant SK Hynix is one of the few positive cases this season, significantly improving sentiment in related sectors. Krinsky acknowledged that this is to some extent a true short-term clearing event—SK Hynix had previously experienced a pullback of about 33%. He believes its stock price is likely to rebound to around $180, but will face pressure again afterward.
Additionally, the Federal Reserve's meeting did not provide directional guidance. The Fed paused interest rate hikes as expected, but both Hammack and Lisa Cook unexpectedly voted in favor of a rate hike, and after the meeting, the Fed Chair held a hawkish press conference, yet the stock market still rose. Notably, the Fed has incorporated AI-related memory demand into its inflation assessment framework—this means that the current storage boom driving the semiconductor rebound has, to some extent, become a potential variable for the Fed's tightening monetary policy.
Two Histories, One November
The divergence of these two narratives ultimately boils down to a methodological question: can the statistical regularities of average data from 1998 overcome a single but highly fitting historical simulation?
Deutsche Bank's data wins by sample size, but as Reid himself warned, averages obscure extreme scenarios. Krinsky's rebuttal logic is that the statistical premise of average years does not hold for 2026—the S&P 500 is less than 1% from its all-time high, the options market shows no panic, only one sector is in the oversold range, and both flagship tech earnings reports have been sold off. When most people are referencing the same Christmas rally chart, the clearing effect has already been consumed by the expectation itself.
In this framework, the clearest path for the current market may be: SOXX completes its final rebound in the coming days, reaching the 550 to 570 range, followed by a directional reversal around the midterm election week. However, if Microsoft's upward momentum continues and Google's decline is supported tomorrow, the Christmas rally script may not be without room for a turnaround. The answer may already be evident in this Friday's closing price.
Risk Warning and Disclaimer
The market carries risks, and investment requires caution. This article does not constitute personal investment advice and does not take into account the specific investment goals, financial situation, or needs of individual users. Users should consider whether any opinions, views, or conclusions in this article align with their specific circumstances. Investing based on this carries responsibility.