
AI chip supply cannot meet demand, yet Intel plummeted by 20%
Intel CEO Pat Gelsinger. Image processed by AI
Written by|Xiao Jing
Edited by|Xu Qingyang
On October 29, local time in the United States, Intel announced its third-quarter financial report for 2026. The report showed that Intel's revenue for the quarter reached $16.51 billion, a year-on-year increase of 21%; net profit was $3.32 billion, a year-on-year decrease of 18%; diluted earnings per share were $0.60, a year-on-year decrease of 33%.
Excluding equity investment income, restructuring costs, stock incentives, and other items, under Non-GAAP standards, Intel's net profit for the third quarter was $2.756 billion, a year-on-year increase of 169%; diluted earnings per share were $0.52, a year-on-year increase of 126%, exceeding the market's previous expectation of $0.40.
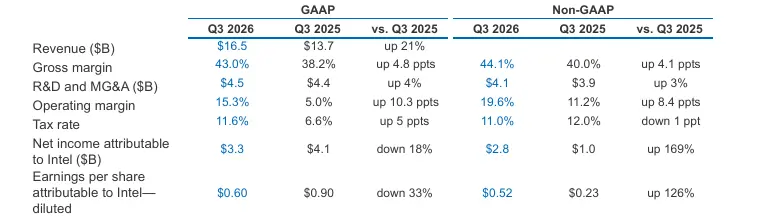
At the same time, Intel's gross margin for the quarter reached 43%, and under Non-GAAP standards, it was 44.1%, an increase of 4.8 and 4.1 percentage points year-on-year, respectively.
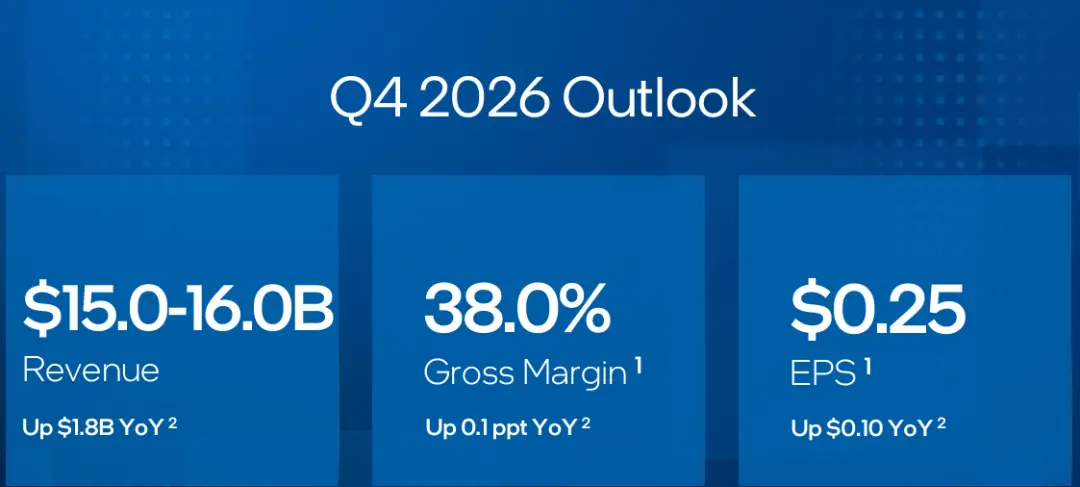
However, the revenue growth did not lead to the sustained upward adjustments expected by the market. The company expects fourth-quarter revenue to be between $15 billion and $16 billion, with Non-GAAP diluted earnings per share of only $0.25, significantly lower than Wall Street's expectations of about $17.07 billion in revenue and $0.43 in earnings per share.
Before the financial report was released, Intel's stock price had already fallen by 3.6% during regular trading on October 29, closing at $92.07. After the performance and guidance were announced, the after-hours stock price dropped more than 20% at one point.
The direct reason for the sharp decline in stock price was the significantly lower-than-expected revenue and profit guidance for the fourth quarter. Despite strong demand for AI servers, concerns arose among investors about whether Intel could continuously convert AI demand into revenue and profit due to weak PC business, limited CPU supply, and production capacity losses caused by incidents at its Israeli factory.
01 The Xeon Chips Are Selling Like Hotcakes, But PCs Are Falling Behind
The Data Center and Artificial Intelligence Group (DCAI) is Intel's fastest-growing business this quarter.
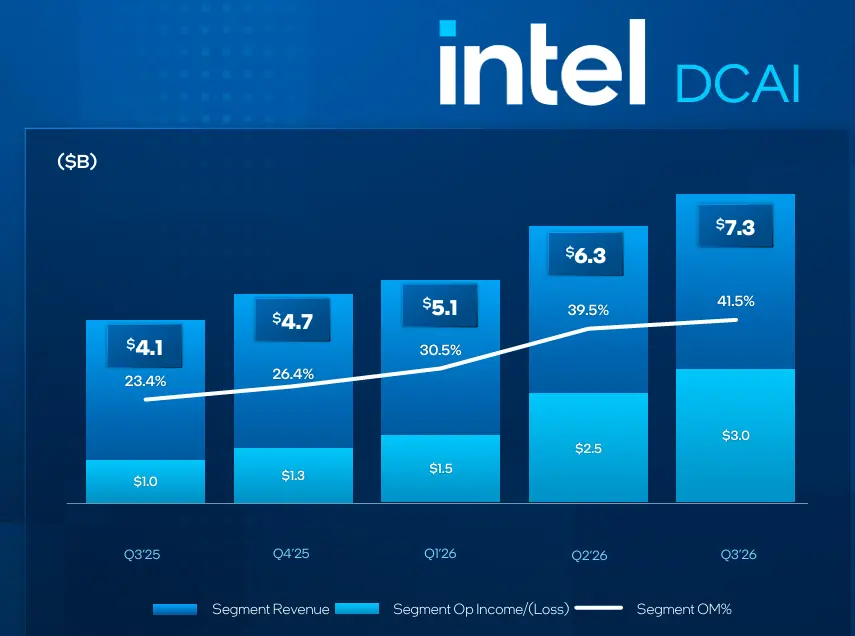
In the third quarter, this division's revenue reached $7.318 billion, a year-on-year increase of 78%; operating profit was $3.039 billion, more than double the $964 million from the same period last year, with an operating margin of 41.5%.
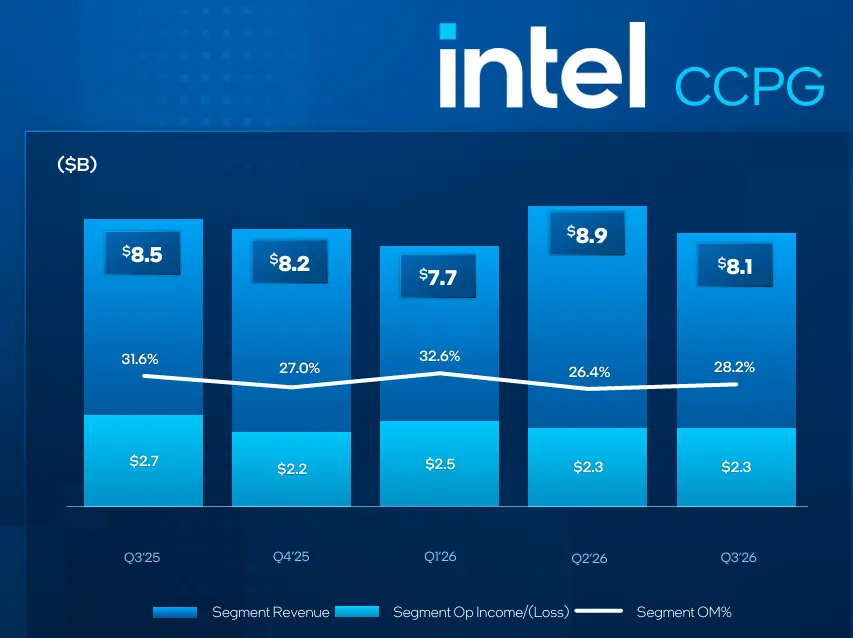
The Client Computing and Physical AI Group (CCPG) reported revenue of $8.097 billion, a year-on-year decrease of 5%; operating profit was $2.285 billion, down from $2.694 billion in the same period last year, with an operating margin of 28.2%.
The growth in data center demand is related to the boom in AI infrastructure construction. As AI model inference and agent applications increase, servers need to handle task scheduling, data processing, memory management, and other general computing tasks, leading to increased configuration requirements for CPUs in AI server systems.
Intel CEO Pat Gelsinger stated in the financial report that despite short-term pressures in the PC industry, demand for the company's CPUs remains strong. The company's top priority is to increase supply to meet the demand for Xeon processors while strengthening its product portfolio and roadmap.
Intel CFO David Zinsner also mentioned that the third quarter saw the strongest revenue growth in the data center business in 15 years, with revenue, gross margin, and earnings per share all exceeding previous guidance.
Supply remains a significant constraint on growth. Intel has previously stated that the growth rate of server CPU demand exceeds the pace of supply expansion for some products. The company is working to increase factory output, improve yield rates, and shorten production cycles to boost Xeon processor supply.
In terms of products, Intel is advancing the next-generation Xeon processor, Diamond Rapids, aimed at high-performance computing, AI inference, and enterprise workloads. Intel also showcased rack-level designs based on Xeon processors and the D series of standalone GPU products for AI inference at the OCP Global Summit.
In the client market, the situation is different. Intel's PC chip revenue for the third quarter was $8.1 billion, a year-on-year decrease of 5%, falling short of the market's previous expectation of about $8.98 billion.
Zinsner expects the slowdown in the PC market to last at least until the first half of 2027. Rising prices for memory chips are also putting pressure on the PC market, as increased memory and storage costs may raise the prices of end devices, thereby affecting consumer purchasing willingness.
02 Foundry Revenue Grows 58%, Still Posts a Loss of $1.85 Billion in a Single Quarter
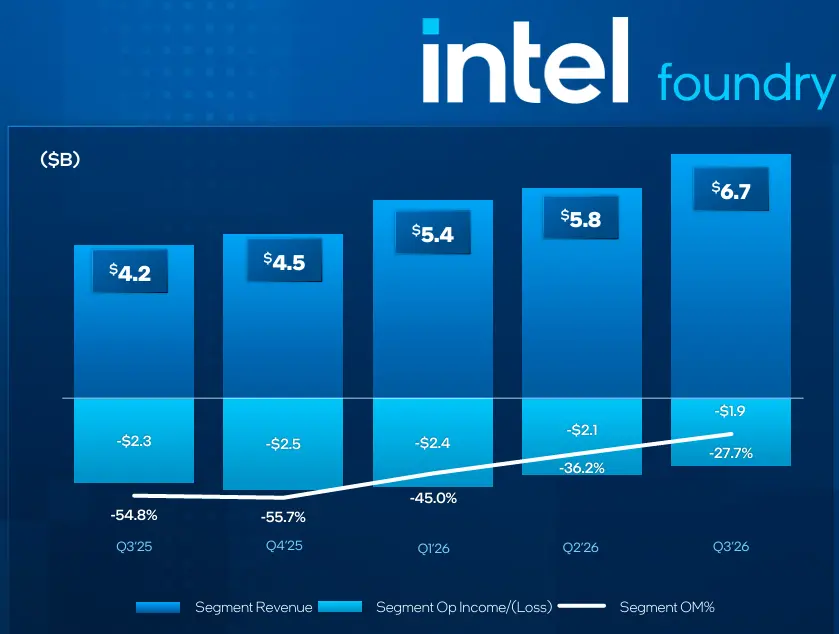
Intel's foundry business revenue for the third quarter was $6.697 billion, a year-on-year increase of 58%. However, this figure includes internal manufacturing transactions and cannot be directly regarded as foundry revenue contributed by external customers.
Internal manufacturing costs paid by Intel's product division to the foundry division are also included in foundry revenue. In the third quarter, the offset amount for internal transactions between the product and foundry divisions was $6.291 billion. Only after deducting internal transactions does the revenue in the consolidated financial statements reflect the actual total revenue recognized by the company externally.
In terms of profitability, the foundry business is still under significant pressure. In the third quarter, this division posted an operating loss of $1.853 billion, narrowing from a loss of $2.321 billion in the same period last year, with an operating loss margin of about 27.7%.
In advanced processes, Intel's 18A has entered the mass production stage. Intel previously announced that the third-generation Core Ultra processor (Panther Lake) using the 18A process has entered large-scale manufacturing. This product utilizes ASML's High-NA EUV technology.
In the second quarter of this year, Intel also launched the Xeon 6+ processor, becoming the first server-grade product to use the 18A process.
Following 18A, Intel is advancing the 18A-P and 14A processes. The company previously disclosed that 18A-P has entered the risk trial production stage, further optimizing performance, power consumption, and thermal characteristics. In the third quarter, Intel released version 0.9 of the process design kit (PDK) for the 14A process, allowing potential customers to conduct chip design and verification work.
The 14A process is key to Intel's next stage of advanced process competition. Compared to 18A, 14A requires further enhancement of manufacturing capabilities and attracting external customers. Intel previously expected that customers would gradually make choices regarding the 14A process from the second half of 2026 to the first half of 2027.
Advanced packaging is another business path. Intel is advancing packaging technologies such as EMIB-T and collaborating with Chinese company Lens Technology to explore the combination of glass processing technology and advanced semiconductor packaging.
TD Cowen analyst Joshua Buchalter believes that Intel's EMIB-T advanced packaging technology is forming valuable external market opportunities, and the company plans to expand related customer business next year. However, he also pointed out that the key factor affecting Intel's foundry business valuation remains whether it can secure large-scale front-end wafer manufacturing customers.
03 Capital Expenditure Rises to $20 Billion, Expected to Continue Increasing in 2027
Intel is expanding its manufacturing investments again.
In the third quarter, the company's capital expenditure reached $4.219 billion, up from $2.956 billion in the same period last year. During the same period, cash flow from operating activities was $5.082 billion, and adjusted free cash flow was $1.639 billion.
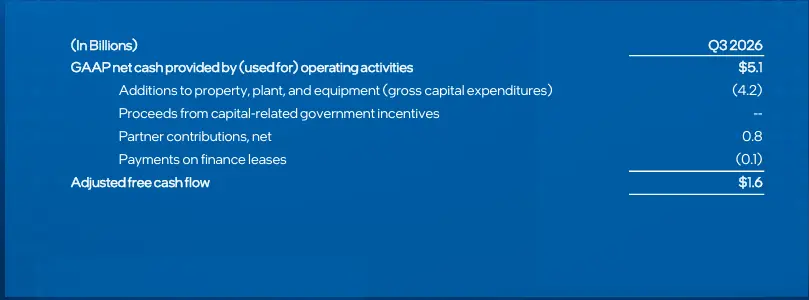
Intel has raised its full-year capital expenditure expectation for 2026 from the previous $18 billion to $20 billion. Zinsner stated that to meet future growth demands for products and foundry businesses, Intel will significantly increase capital investment in 2027.
Investment focuses include manufacturing equipment, cleanroom space, and substrate capacity. Intel needs to expand production capacity for advanced processes while improving the utilization of existing factories to meet the demand for Xeon processors and other products.
However, the funding requirements for manufacturing investments are increasing. In August, Intel completed a public stock offering of approximately $23 billion to support future growth and maintain its balance sheet. According to the third-quarter financial report, the public stock offering brought the company about $22.617 billion in net cash income.
This also raises a question: Intel needs to balance increasing capacity and controlling capital consumption.
Unlike light-asset chip design companies like Arm, Intel needs to bear long-term expenses such as factory construction, equipment procurement, process research and development, and capacity ramp-up. New capacity requires going through stages such as equipment installation, process validation, customer certification, and production ramp-up before generating stable revenue.
If demand for server CPUs remains strong, the new capacity is expected to convert into revenue; if PC demand continues to weaken, or if external foundry customer orders are fulfilled slower than expected, fixed asset investments may further depress profit margins and cash returns.
Changes in gross margin also reflect this pressure. Intel's Non-GAAP gross margin for the third quarter reached 44.1%, an increase of 4.1 percentage points year-on-year. However, the guidance for the fourth quarter's Non-GAAP gross margin is only 38%, a decrease of 6.1 percentage points.
As capital expenditure continues to increase, whether gross margins can remain at a high level will directly impact the financial sustainability of Intel's expansion plans.
04 Google, Oracle, and Meta Join the Collaboration List
Intel is expanding its collaborations with cloud computing vendors, AI companies, and device suppliers, attempting to gain more business opportunities through processors, custom chips, and advanced packaging.
In the third quarter, Intel announced a multi-year collaboration with Oracle to expand the application of Xeon processors in Oracle Cloud Infrastructure (OCI). The collaboration covers current and future Xeon platforms, including the OCI X14 product, which plans to use the next-generation server processor Diamond Rapids.
Intel also disclosed that Meta's Muse Spark Open has been tested and is running on the upcoming GPU D series and Xeon platform. The GPU D series was previously codenamed Crescent Island, primarily targeting AI inference workloads.
In the client field, Intel collaborated with Google to launch the first Googlebook devices, using the third-generation Core Ultra processors, with related products involving manufacturers such as Acer, Asus, and Lenovo.
In addition, Intel has collaborated with AMD to integrate x86 CPU optimizations for PyTorch into the oneDNN software library, improving the development and deployment experience of AI applications on the CPU platforms of both companies.
Intel also announced a partnership with SAP to connect enterprise IT systems with operational technology that controls physical devices and production processes, expanding the application of physical AI in industrial scenarios.
These collaborations involve cloud computing, AI inference, PC, and industrial applications, covering several directions where Intel currently hopes to expand its market share.
However, it is important to distinguish between partnerships, product testing, and actual purchase orders. Intel has not disclosed the specific purchase amounts, long-term order scales, or revenue contributions corresponding to the aforementioned collaborations in this financial report, and the partnership announcements cannot be directly counted as realized new revenue.
The expansion of external customers in the foundry business also faces similar issues. The market has previously focused on news that Google's custom TPU chips may be manufactured by Intel, as well as potential collaborations between NVIDIA and Intel in manufacturing. However, as of this financial report, the relevant order scales and formal manufacturing agreements still lack official confirmation from Intel.
In terms of competition, Intel needs to face TSMC's advantages in advanced processes and customer relationships, as well as competition from companies like AMD and NVIDIA in different computing markets. Large tech companies such as Microsoft, Google, Amazon, and Meta are also developing their own chips to reduce dependence on a single supplier.
05 Israeli Factory Accident Drags Down Guidance
The fourth-quarter performance guidance, which is below market expectations, is the direct reason for Intel's stock price decline following this financial report, while the Israeli factory accident has further increased short-term supply and profit pressures.
An explosion occurred at Intel's factory in Kiryat Gat, Israel, in October, causing the factory to halt production for about two weeks. This factory primarily uses Intel's 10nm process technology to produce some data center chips.
Zinsner stated that this accident is expected to reduce fourth-quarter revenue by approximately $300 million and lower gross margins by about 200 basis points. The factory plans to gradually resume production around the end of October, but the company is still inspecting the damaged wafers to confirm which products can continue to be used.
Intel expects that the accident may also have a similar scale of impact on first-quarter revenue in 2027. If the damaged wafers cannot be restored, the impact may extend for a longer period.
This further complicates the supply constraints that Intel was already facing. The company needs to increase the production of Xeon processors while also dealing with the production losses caused by the factory accident.
For Intel, under the leadership of Pat Gelsinger, three issues need to be addressed moving forward: increasing Xeon processor supply, controlling cost pressures from factory expansion, and converting advancements in 18A and 14A technologies into external customer orders.
The revenue guidance of $15 billion to $16 billion for the fourth quarter already reflects the pressures on the company's short-term growth. The PC market is expected to remain weak at least until the first half of 2027, and the recovery of production at the Israeli factory also needs to be monitored.
The market's valuation of Intel has already reflected some recovery expectations in advance. Reuters noted that Intel's stock price has more than doubled this year, as investors are reassessing its growth potential and the funding required for manufacturing business expansion.