
Morgan Stanley: Traditional server revenue increased by 87%, storage is still in the early cycle
Written by: Rita
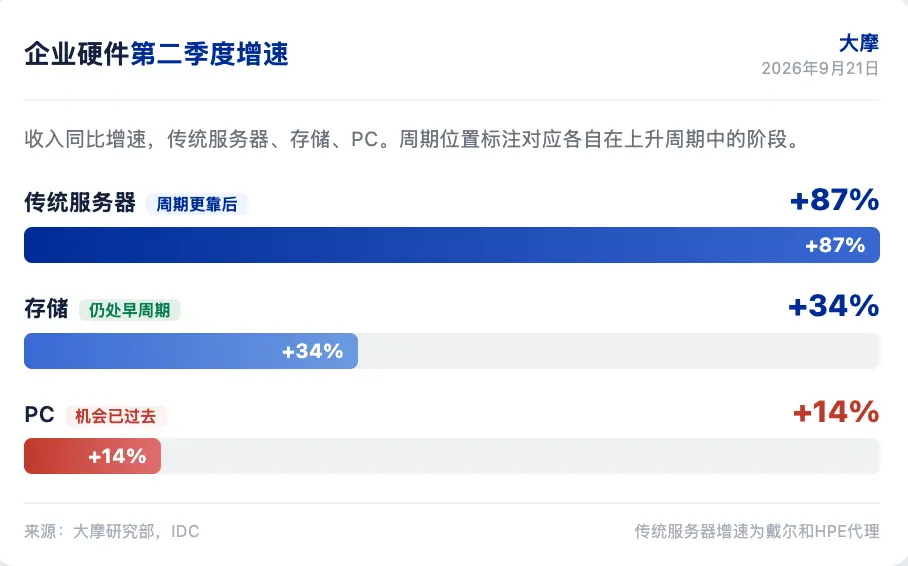
Corporate hardware spending strengthened significantly in the second quarter. Morgan Stanley's IT hardware report released on September 21, 2026, noted that traditional server revenue grew by 87% year-over-year, storage grew by 34%, and PC growth was 14%, all reaching the highest growth rates in over a decade, excluding the pandemic. However, the market has already seen through this strength; among eight corporate hardware stocks, six had valuation multiples lower after earnings reports than before, despite an average upward revision of 12% in earnings per share for the next fiscal year. Morgan Stanley believes that whether spending is strong is no longer the key issue; the critical question is how long this cycle can last.
Morgan Stanley's core judgment is that storage is still in the early stages of an upward cycle, the server cycle is further along, and the PC market has rapidly deteriorated. The firm prefers P and SNX, followed by HPE, maintains a neutral stance on Dell, and gives HPQ a downgrade. Dell is executing the strongest, but its valuation has already reflected this; HPQ faces dual pressures from PC demand and profit margins.
Corporate Hardware Spending Remains Strong
Corporate hardware spending grew significantly in the second quarter. Traditional server revenue increased by 87% year-over-year, storage grew by 34%, accelerating from 23% in the first quarter, and PC revenue grew by 14%. Morgan Stanley pointed out that these growth rates are at their highest levels in over a decade, excluding the pandemic. However, the market has seen through the recent strength; among eight corporate OEM, VAR, and distribution stocks, six had valuation multiples lower after earnings reports than before, despite an average upward revision of 12% in earnings per share for the next fiscal year, with the average price-to-earnings ratio compressing by about one multiple.
Morgan Stanley's AlphaWise survey shows that the current strength is mainly cyclical, driven by typical upgrades and early procurement by large enterprises, with most AI workloads still in the cloud. On-premises AI construction is expanding, but it remains a minority deployment, with the share of on-premises AI workloads expected to decline by 3 percentage points in the coming year. Morgan Stanley believes that Dell and HPE have the opportunity to benefit from the continued on-premises AI, which is a contributing factor to the sustained outperformance of their stock prices after earnings reports.
Storage Still in Early Cycle
Storage growth is accelerating and is in the early stages of an upward cycle. Morgan Stanley noted that the server cycle is further along, and most opportunities in the PC market have already passed. Storage has the longest runway among the three. In the second quarter, P had the largest share growth in external OEM storage data, with revenue share growth second only to Dell. P's pricing is more moderate than NTAP, and its product efficiency is higher, leading enterprises to increasingly prefer to assign new storage projects to P.
Morgan Stanley reiterated its overweight rating on P, with a target price of $119. P's current price-to-earnings ratio is about 29 times, which is 14% lower than the average over the past three years. Peer corporate OEMs are currently trading more than two standard deviations above historical average valuations. Morgan Stanley believes the market underestimates P's potential for earnings revisions, especially given record growth and new orders from hyperscale customers. The analyst day on September 23 is an important catalyst, with long-term operating margin guidance being a key indicator. An operating margin in the low 20% range would be disappointing, mid-20% would meet expectations, and high 20% would be a positive surprise.
Server Profit Margin Stacking at Unprecedented Levels
The profit margins for traditional servers have reached unprecedented levels. Both Dell and HPE are experiencing this trend. For example, Dell's low-margin AI servers accounted for 52% of ISG revenue, up from 49% a year ago, but ISG's gross margin expanded by 200 basis points year-over-year to 23.6%. Morgan Stanley estimates that even if AI server and storage gross margins increase year-over-year, Dell's traditional server gross margin has exceeded 30% for the first time, up about 9 percentage points year-over-year, while NAND and DRAM prices have risen year-over-year by 340% to 550%, which historically accounted for about 40% of the traditional server bill of materials.
Dell and HPE are actively repricing, with supply scarcity, rich configurations, and inelastic demand driving prices far beyond historical levels. Morgan Stanley estimates that if Dell's F1Q27 server units, ASP, and revenue remain unchanged, but traditional server gross margins normalize to the low 20% range, F1H27 earnings per share would drop by 13%, approximately $1.52. About $3.75 of FY27 earnings per share comes from the profit margin stacking of traditional servers. Morgan Stanley believes that as long as memory prices continue to rise and supply remains constrained, the profit margin stacking will not disappear quickly. The firm raised Dell's FY27 and FY28 traditional server gross margins by 50 to 80 basis points, increasing the target price from $499 to $511.
Dell Executes Strongly but Valuation is High
Dell's execution is extremely strong, and the market is willing to reward the best performers. Dell's revenue grew by 58% year-over-year in the second quarter, and net profit grew by 189%, surpassing Lenovo, HPE, P, NTAP, and HPQ. Dell's stock price rose by 34% in 2.5 weeks, while other hardware OEMs averaged a 9% increase. Dell's relative historical valuation premium is also higher than its peers. Morgan Stanley pointed out that Dell is an all-weather winner among OEMs, a cloud AI winner, an on-premises winner, a geopolitical winner, and a supply chain winner.
However, Morgan Stanley maintains a neutral rating on Dell, with a target price of $511. The reasoning is that the market has already reflected strong execution, and the valuation premium is significant, while the sustainability of earnings in the later stages of the cycle is uncertain. Early procurement of traditional servers and profit margin stacking will eventually normalize, at which point AI growth, market share gains, storage outperformance, and operational leverage will be needed to support earnings. Morgan Stanley believes that Dell's recent execution is indisputable, but at the current valuation level, the positive asymmetry of risk and return is limited.
P and SNX are the Most Preferred Targets
Morgan Stanley's most preferred corporate hardware targets are P and SNX, followed by HPE. P is the market leader in the all-flash array segment, continuously gaining market share, benefiting from all-flash growth outpacing the overall enterprise storage market. P's hyperscale business provides long-term revenue and gross margin upside potential, which the market has not yet fully priced in. P's valuation is below historical averages, while peer corporate OEMs are above historical averages by more than two standard deviations.
SNX benefits from two lines: enterprise infrastructure distribution and capital expenditures from hyperscale customers. Morgan Stanley expects SNX's distribution business total billings to compound grow by 11% by FY28, exceeding peers; Hyve's contract manufacturing business total billings are expected to compound grow by 64%, with new hyperscale projects ramping up, pushing the proportion of operating profit to about 50%, driving earnings per share to compound grow by over 30%. SNX's current valuation is about 10 times FY27 earnings per share and 8 times FY28 earnings per share, and Morgan Stanley believes the market underestimates the potential for market share gains, earnings growth, and the value of Hyve options. The target price is $334.
HPQ Faces Dual Pressure
HPQ faces dual pressures from PC demand and profit margins. In the second quarter, the operating profit margin for personal systems was 4.6%, approximately 4.3% after excluding tariff refunds, a year-over-year decline of about 110 basis points. Dell's CSG operating profit margin is about 330 basis points higher than HPQ's, expanding by about 120 basis points year-over-year to 7.6%. Morgan Stanley pointed out that the execution gap among PC OEMs is widening. HPQ's management believes that the fourth quarter will be the low point for personal systems profit margins, expecting recovery in FY27, but Morgan Stanley believes this recovery faces pressures from component inflation and weak unit sales.
HPQ's valuation is at 11 times Street FY27 earnings per share and 12.5 times MSE earnings per share, and Morgan Stanley believes it is becoming increasingly difficult to justify. HPQ is the only OEM within coverage that expanded its price-to-earnings ratio before earnings reports, despite the smallest earnings revision. Historically, HPQ has traded at about 7 times price-to-earnings ratio during periods of year-over-year declines in revenue and profit. Morgan Stanley maintains a downgrade rating, with a target price of $19, indicating over 40% downside from current levels. The firm expects HPQ's FY27 revenue to decline by 2% and earnings per share to drop by 16%, both below market consensus.
Catalysts Arriving Intensively
Several important catalysts are coming in the next few weeks. On September 22, Dell's COO meeting, Morgan Stanley will focus on supply chain allocation, traditional server pricing, AI server economics, and storage add-ons. On September 23, P's analyst day will focus on hyperscale economics and long-term operating margin guidance. On September 24, SNX's earnings report will focus on distribution market share gains and Hyve details. On September 30, HPE's network analyst day will focus on whether the integration of Aruba and Juniper translates into sustained growth and the scale of AMD Helios opportunities.
In early October, IDC will release preliminary third-quarter PC data, providing first-hand readings of the severity of the PC deterioration. Monthly revenue from Taiwanese ODMs will be announced before October 10, providing transparency on AI servers, traditional servers, and laptop shipments. Supply chain data points, especially regarding DRAM and NAND supply and pricing, are key to assessing OEM pricing power and the sustainability of server profit margin stacking. Monthly VAR checks and CIO surveys will provide evidence on whether server intentions have peaked and whether storage and networking are accelerating.
If storage and server demand continue to exceed supply in 2027, will the valuation compression of corporate hardware stocks reverse, or will the market continue to price in the peak of the cycle in advance?
Disclaimer
This article is a compilation and interpretation of third-party brokerage research reports (Morgan Stanley, September 21, 2026) by Chao Xiang Research, combined with publicly available market information. The ratings, target prices, earnings forecasts, and related judgments quoted in this article are the views of the brokerage analysts and represent the positions of their respective institutions, not the views of Chao Xiang Research, and do not constitute any investment advice.
The market carries risks, and decisions should be made independently. This article should not be used as a basis for buying or selling any securities.