
Circle: Performance is "inflated," major channel players "bite back," expanding the ecosystem is the only way out
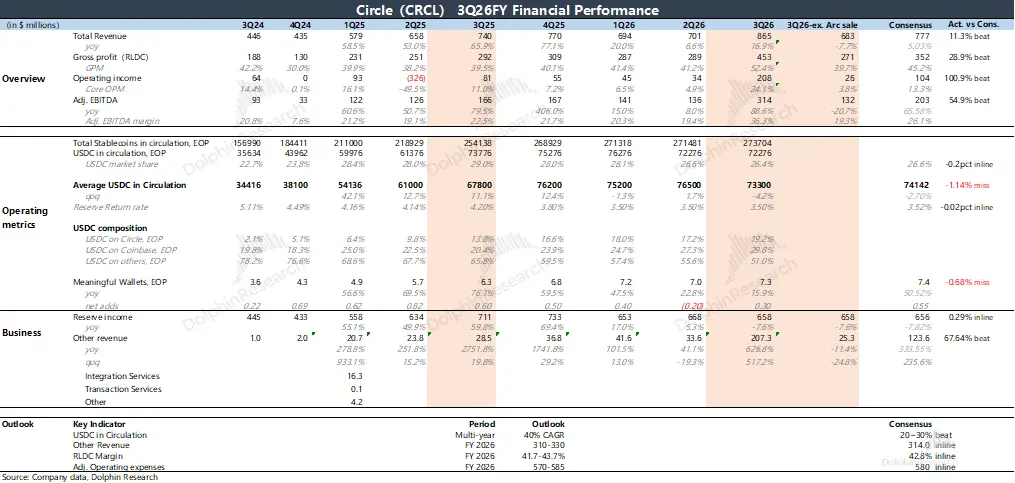
Circle released its Q3 report before the market opened on November 4 in the Eastern US. Overall, the performance was mainly driven by the "better-than-expected" revenue from Arc token sales, but excluding this part, the actual performance was average, confirming concerns about funding prior to the financial report.
Specifically:
1. Reserve interest income declined as expected
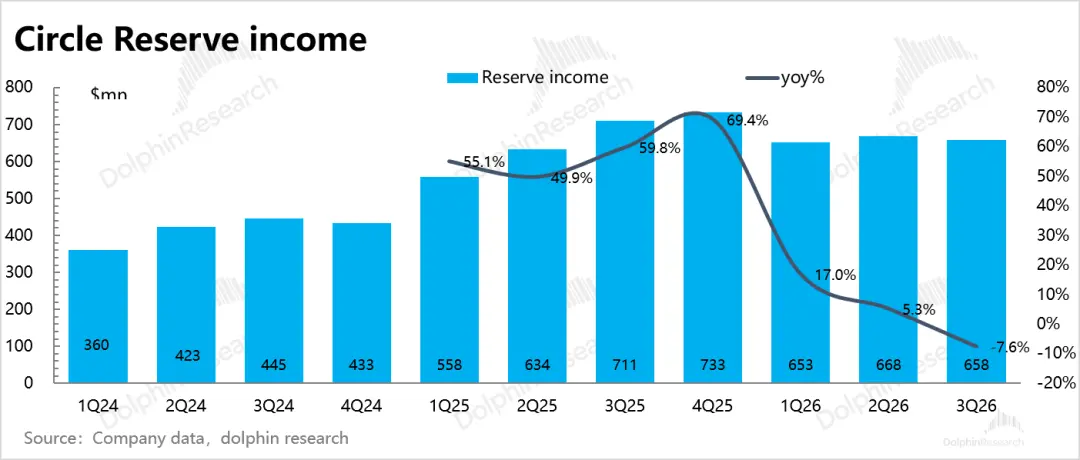
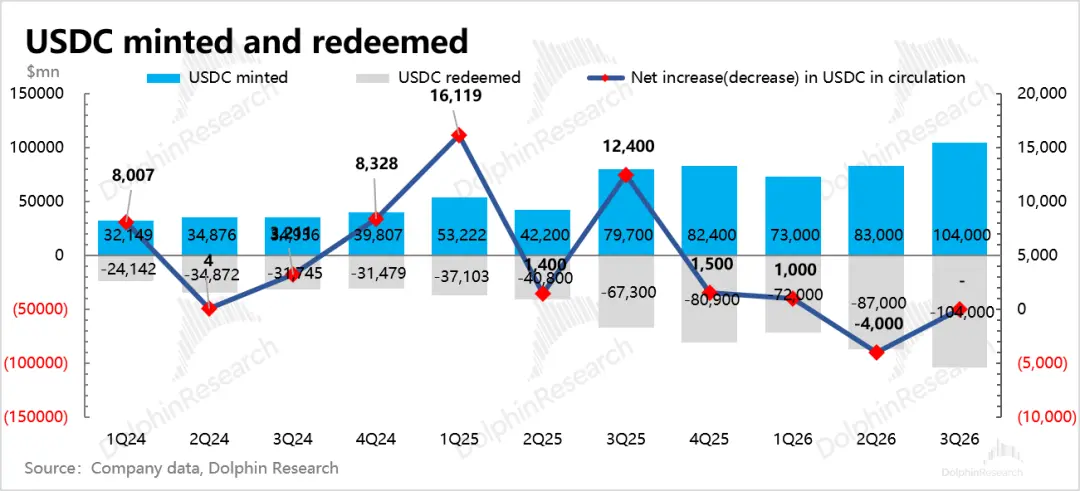
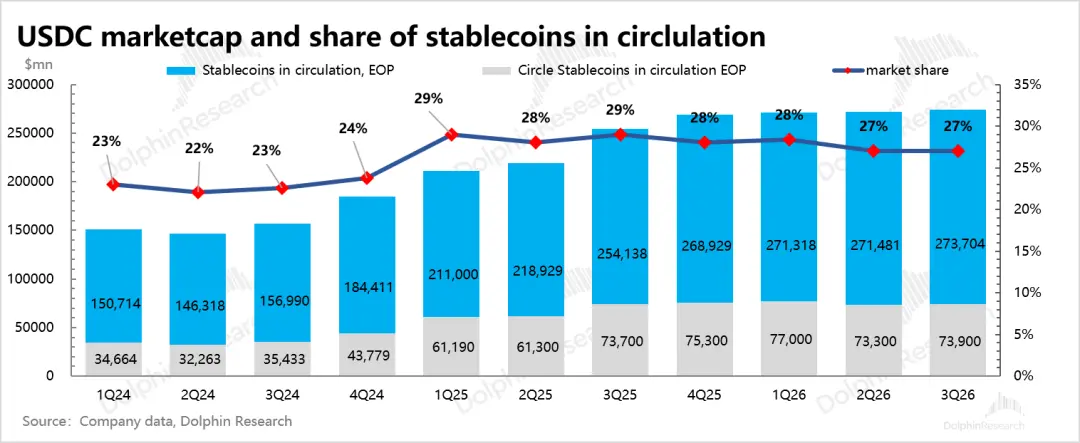
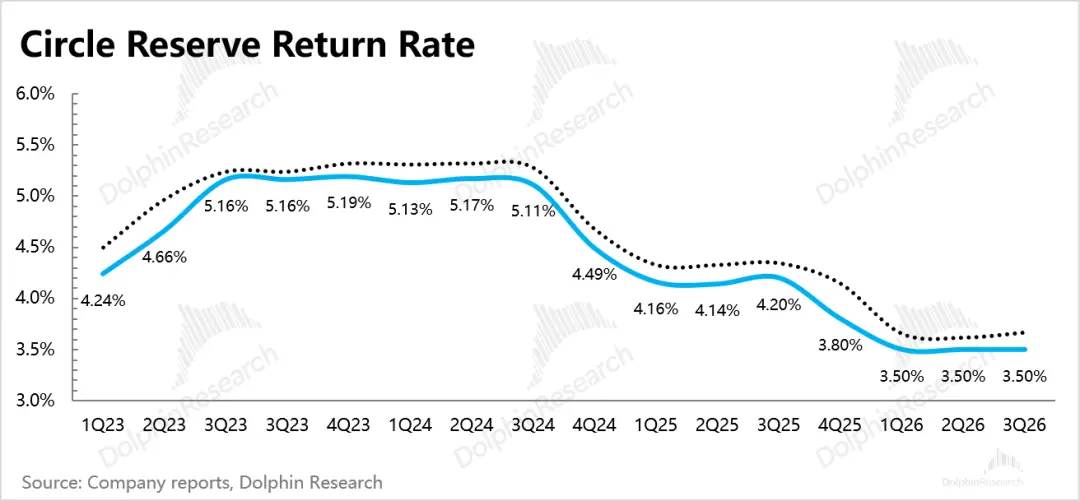
Q3 reserve interest income was 660 million, in line with expectations. Despite an 8% year-on-year increase in USDC market capitalization, the interest income decreased by 8% due to a decline in interest rates. On a quarter-on-quarter basis, the average circulation scale of USDC in Q3 was 73.3 billion, a decrease of 4% compared to Q2.
2. Arc token sales confirmed faster than expected
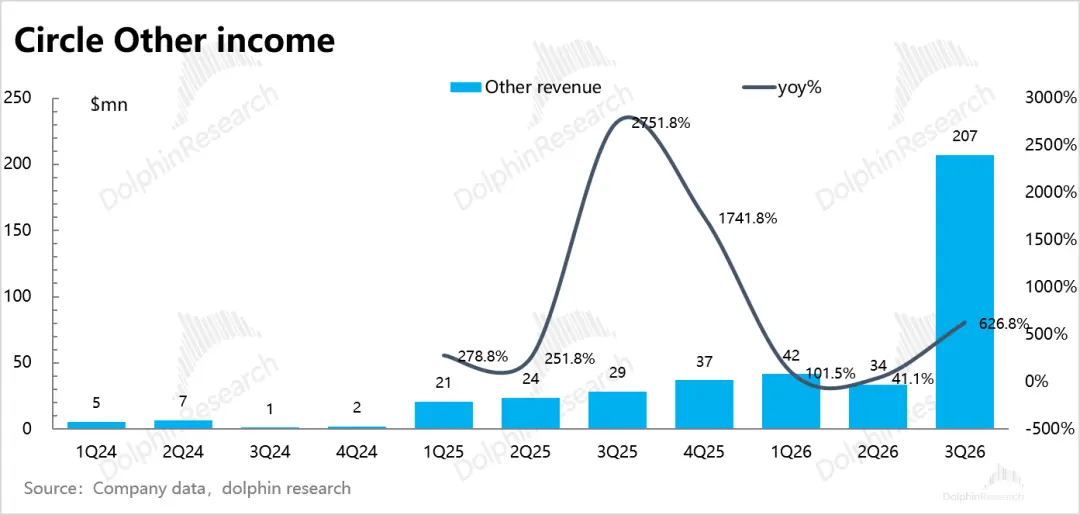
Q3 other income exceeded 200 million, with Arc token sales contributing 180 million, confirming a pace that exceeded market expectations (estimated at 90 million) and the original annual guidance of 180 million.
However, this income is not stable or sustainable; it is more of a one-time revenue. From the unchanged guidance of 310-330 million for other income for the year, it is expected that there will be no such income in Q4. The two rounds of presales this year totaled 224 million, and after confirming 180 million in Q3, there remains 40 million to be confirmed next year.
This Arc token presale attracted a lot of institutional funds. However, it essentially represents a "subscription for equity" in the future earnings of the Arc public chain asset, but Circle initially records it as a prepayment and then recognizes it as income according to the development progress of Arc chain products.
Equity subscription = income, which is inherently strange and does not provide a reliable outlook. Unless there is continuous token "financing," this is a one-time income and does not possess stable and sustainable business characteristics.
Real sustainable income will have to wait until 2027, coming from transaction fees, staking income, and charges from the CPN payment network of Arc. The ARC presale merely realized part of the future value in advance.
3. Major channels "bite back," increasing pressure on interest sharing
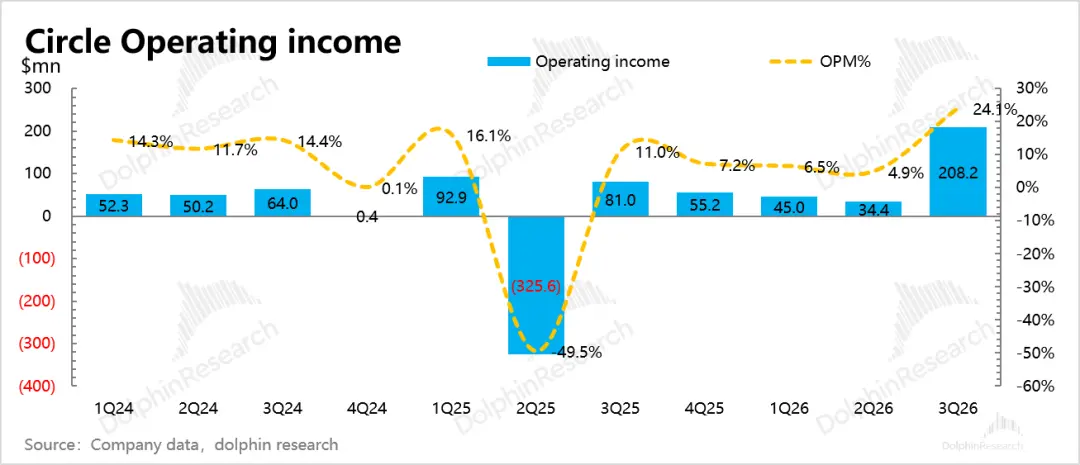
Since Arc token sales have almost zero cost, the 180 million is equivalent to pure profit, leading to "inflated" profits for Q3. If purified, the real profit trend is downward—due to reduced income and relatively rigid expenses, the GAAP operating profit margin dropped by 1 percentage point to 3.9% compared to Q2.
However, Q3 performance also reflected an optimization trend on the expense side due to layoffs. Nearly half of Circle's expenses are personnel salaries, so adjusted operating expenses (excluding layoff compensation) decreased by 5% quarter-on-quarter, reflecting a 5% reduction in staff during the quarter.
It is worth mentioning that starting from Q3, the profit side will gradually reflect the impact of Hyperliquid's interest sharing. A rough calculation suggests that for Circle, the direct loss of gross profit each year is nearly 100 million, with the pressure from revenue fluctuations due to channel resistance becoming evident as early as Q4:
Hyperliquid is the largest on-chain perpetual contract exchange, which has its own public chain. Users trading on it must first deposit USDC as collateral, resulting in a large amount of USDC being held on the platform, approximately 6 billion dollars. For Circle, this is one of the few large pools of USDC outside of exchanges.
Amid the tug-of-war among different stakeholders regarding the CLARITY Act, starting in September, Hyperliquid required Circle to return the reserve interest corresponding to USDC. However, Circle has a pre-agreed profit-sharing agreement with Coinbase—Coinbase takes 100% of the interest for USDC held on its platform, while for USDC interest outside of Coinbase and Circle's custody, Coinbase takes 50%.
Therefore, to meet Hyperliquid's interest return requirements, it must go through Coinbase. The result of this is:
(1) Hyperliquid recovers the vast majority of the interest (estimated at 90%);
(2) Coinbase and Circle each receive 50% less in interest sharing, while this additional 90% of USDC held on the platform increases the AUC, leaving Circle with 10%.
Currently, the total amount of USDC within the Hyperliquid ecosystem is 6.3 billion dollars, and based on a 3.5% rate, the reserve interest income is 228 million annually, with Hyperliquid taking away 90% of that, which is 200 million. The remaining interest of less than 30 million will be split between Coinbase and Circle.
In other words, the originally confirmable 228 million in interest income and 100 million in gross profit (after deducting issuance costs and the original 50% profit-sharing with Coinbase) ultimately results in only 10 million in gross profit.
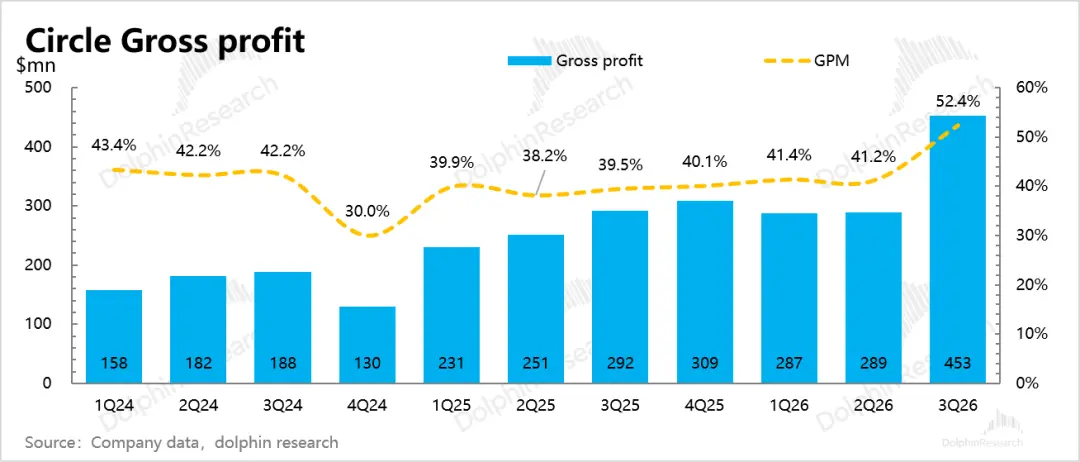
Q3 gross margin was 52.4%, and after excluding the pure profit of 180 million from Arc token sales, the gross margin was 39.5%, showing some impact compared to Q2.
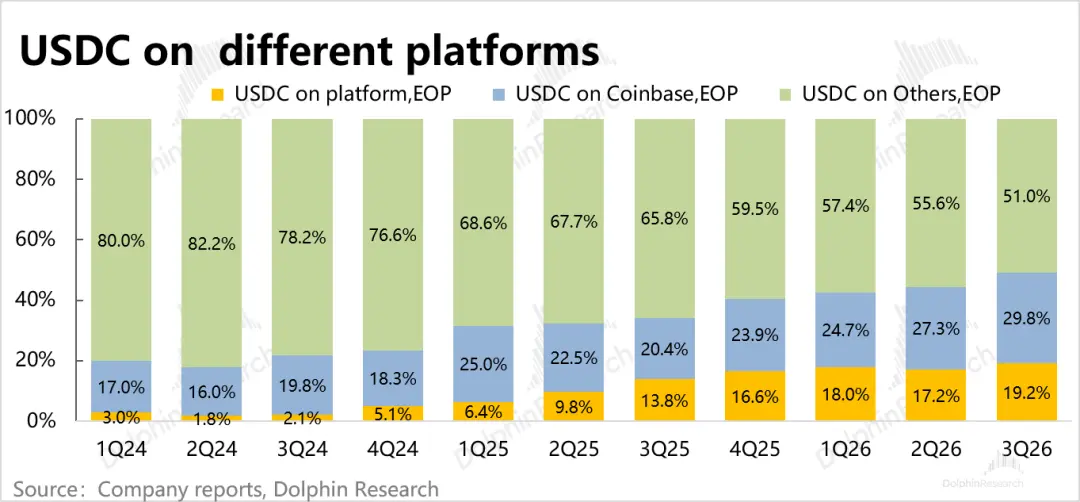
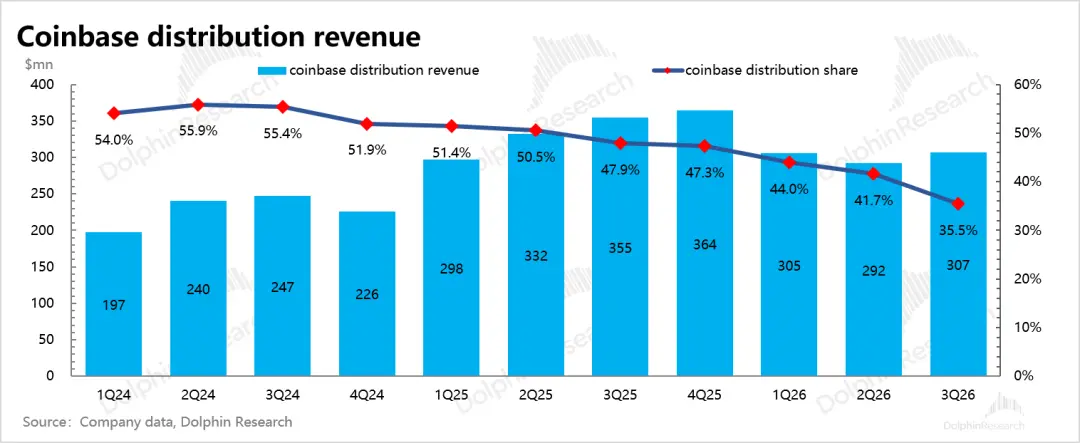
Meanwhile, USDC's share in Coinbase rapidly increased to 30%, but the share of profit-sharing income in Circle's profit-sharing costs quickly decreased to 35%, further confirming the impact of Hyperliquid's "resistance."
- Overview of important indicators
Dolphin's Viewpoint
The Q3 performance merely reflects the "inflation" brought about by differences in confirmation pace, thus failing to deliver any real surprises.
In terms of guidance, both revenue and profit remain unchanged. The RLDC profit margin (revenue minus distribution costs, similar to gross margin) is expected to maintain around 42% for the year, suggesting that the Q4 gross margin will likely drop to just over 30%, indicating a deepening impact from Hyperliquid.
However, since the Hyperliquid event was disclosed in September and its impact is quantifiable, the market should have largely priced it in. The risk lies in whether a second Hyperliquid will emerge in the future.
In addition, competition among stablecoins is intensifying. USDC's advantages mainly lie in its collateralization with US Treasury bonds and high compliance, while being strongly tied to Coinbase, a major centralized digital currency exchange in the US with a more rigid relationship with regulatory authorities.
However, the dynamics of competition among financial institutions are also changing. As USDC's relationship with Binance strengthens—Binance invested 100 million dollars in Circle's equity, expanding and renewing their strategic partnership.
Although the collaboration with Binance primarily targets emerging markets, it inevitably creates subtle effects on the relationship with Coinbase. The Open USD alliance coin, launched by Coinbase and several traditional financial payment chain players, also went live on September 30.
However, Dolphin believes that apart from USDT, USDC still holds a significant advantage over alliance coins, which may struggle to form an effective coalition due to too many stakeholders. In contrast, other financial institutions' constraints on Circle are more likely to stem from risks and impacts arising from demands for interest returns from major channel players like Hyperliquid.
Therefore, although management remains optimistic about the long-term guidance for USDC circulation expansion (with a CAGR growth rate of 40%), both short-term and even mid-term perspectives will need to rely on the prosperity of the Crypto market (the main scenario for USDC) and USDC's breakthrough in the face of competition.