
CoreWeave's default probability exceeds 60%! Jensen Huang "extinguishes the fire": financing costs are decreasing, no need for NVIDIA to backstop
Author: Li Dan
As the default risk of CoreWeave soars to a historic high, with the implied probability of default in the credit market exceeding 60% over the next five years, NVIDIA CEO Jensen Huang stepped in to "extinguish the fire," stating that CoreWeave's financial strength is continuously improving, financing costs are decreasing, and NVIDIA has no need to backstop it.
On Thursday, October 15, Eastern Time, the indicator reflecting the cost of company debt default protection, the five-year credit default swap (CDS) spread for CoreWeave, rose by 74.5 basis points to 1194.5 basis points, setting an intraday historic high. Meanwhile, some of the company's bond yields surged to over 15% to 16%, reflecting a sharp increase in investor concerns about its debt repayment ability.
During an event in Sweden on the same day, Huang stated in a media interview, "CoreWeave's strength is increasing day by day." He expressed optimism about the company and pointed out that its "capital costs are actually decreasing." Regarding market concerns about whether NVIDIA needs to provide financial backing for CoreWeave, Huang clearly stated that he does not believe this is necessary.
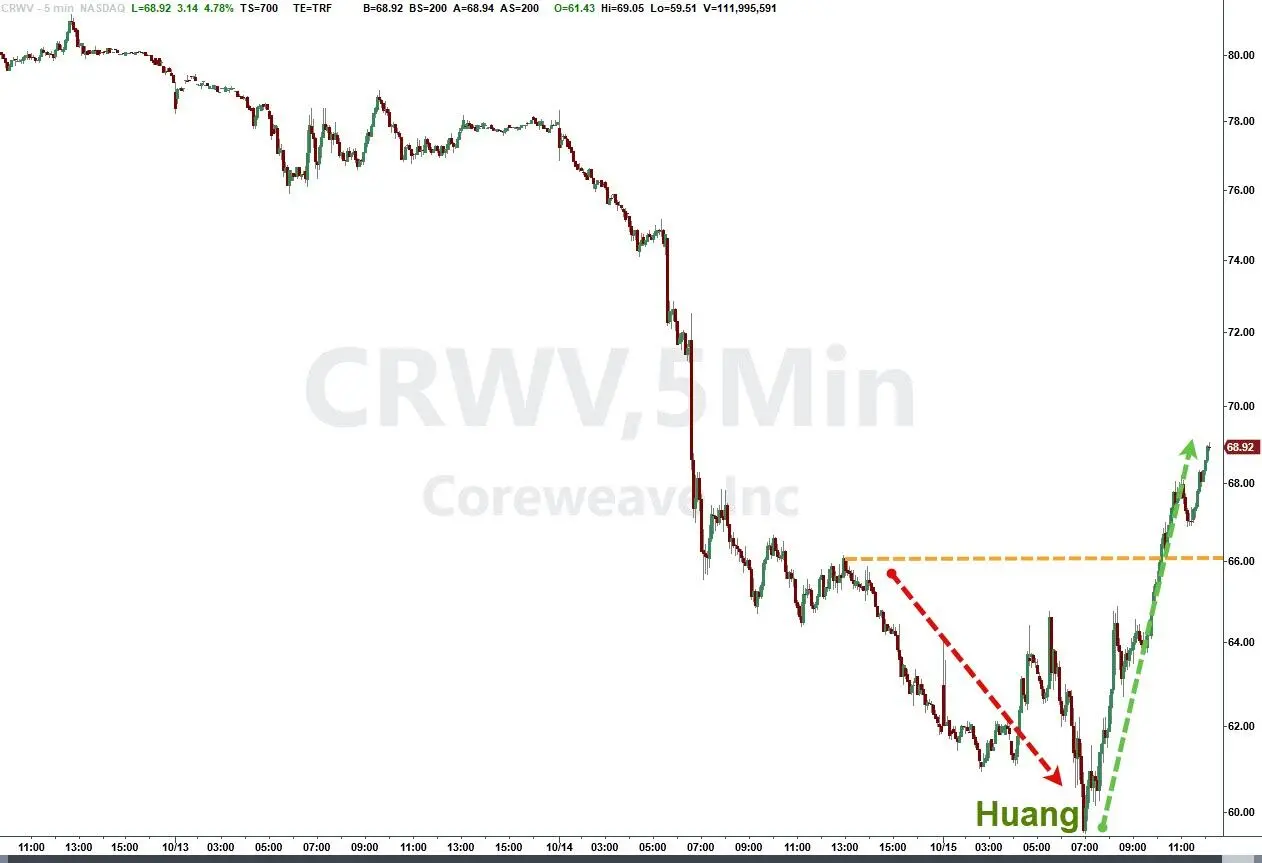
On Thursday, CoreWeave (CRWV) shares opened significantly lower at 6.6%, with the decline at one point expanding to 9.5%. After Huang's remarks, the decline accelerated to narrow, turning positive during the midday session and continuing to rise, with the intraday gain slightly exceeding 6%, rebounding about 17% from the day's low set earlier. By the close, the stock price had risen over 5.9%, reversing three consecutive days of decline, with the cumulative drop for the week narrowing to about 15%.
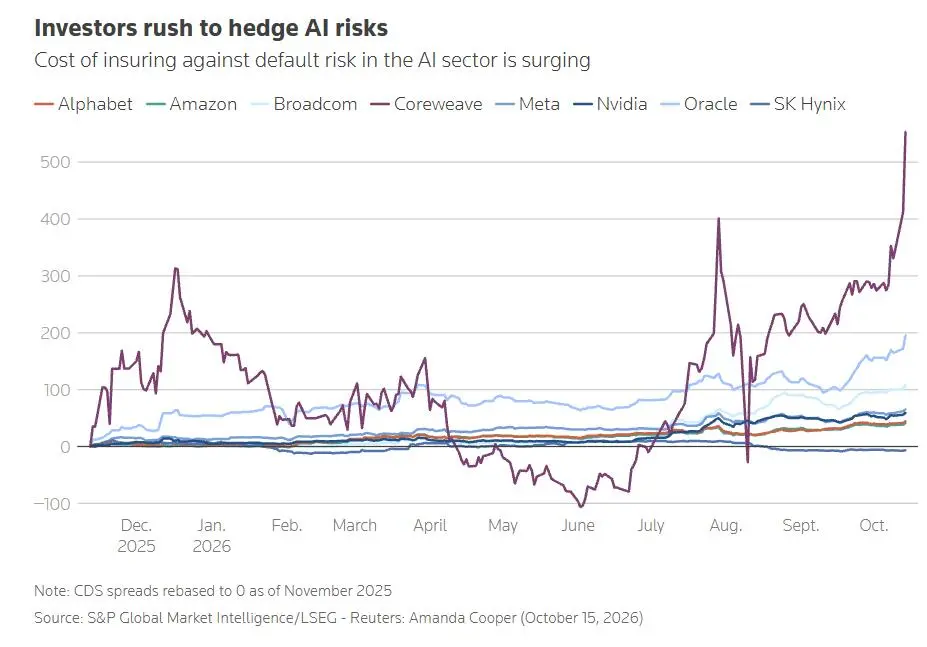
More concerning is that the tension in the credit market is spreading, indicating that investors are reassessing the debt risks behind AI infrastructure investments. Media reports noted that Oracle's five-year CDS spread approached 300 basis points on Thursday, rising about 31 basis points for the day, with the related spreads for Amazon, Google's parent company Alphabet, and Meta all at historic highs; SoftBank's five-year CDS spread widened by 24 basis points in one day; and the CDS spreads for NVIDIA, STMicroelectronics, and SpaceX also rose significantly.
Five-Year CDS Breaks 1190 Basis Points, CoreWeave Bonds Sold Off
CoreWeave is facing a double whammy in both stocks and bonds.
According to ICE Data Services, on Thursday, the five-year CDS spread for CoreWeave reached an intraday high of 1194.5 basis points, setting a record, with the corresponding pricing implying a cumulative default probability of over 60% over the next five years. Data from LSEG and S&P Global Market Intelligence indicated that CoreWeave's CDS spread broke 1100 basis points during the day, corresponding to a five-year default risk of about 64%, up from about 30% a year ago.
CDS is a credit derivative used to hedge against debt default risk, and its spread typically rises as market concerns about the issuer's repayment ability increase. However, the implied default probability of a CDS depends on the pricing model and related assumptions and does not mean that the actual default probability for the company over the next five years has been precisely determined.
The performance in the bond market is similarly grim. Bloomberg cited market data stating that on Thursday, the price of CoreWeave's bonds maturing in 2031 with a coupon rate of 9% fell by about 3.3 cents to 79.9 cents per dollar of face value, with the yield rising to 15.6%; another bond with a coupon rate of 9.75%, also maturing in 2031, fell by about 2.6 cents to 78.65 cents, with the yield rising to 16.2%.
Reuters reported that CoreWeave's bonds maturing in 2032 were trading at about 78 cents per dollar of face value on the Tradeweb platform, with yields exceeding 16%. Different bonds have varying maturity dates, coupon rates, and trading prices, but all indicate that investors are demanding higher risk compensation.
The significant drop in bond prices below face value and soaring yields mean that CoreWeave may face higher costs for future financing or refinancing through the bond market.
CoreWeave co-founder Brannin McBee recently stated in an interview with the Financial Times that the company hopes to obtain an investment-grade credit rating to open up broader financing channels, potentially allowing it to borrow from an "unlimited" pool of funds. This goal stands in stark contrast to the currently high bond yields: as investor concerns about repayment ability have not yet dissipated, whether the company can continue to secure financing at lower costs remains to be seen in the market.
Oracle, SoftBank, and Other AI-Related Companies See Rising CDS, Credit Risk Spreading Across the Industry
CoreWeave is not the only AI-related company facing pressure in the credit market.
On Thursday, the five-year CDS spread for Oracle was reported at 288 basis points, unchanged from the previous trading day but widened by 28 basis points from 260 basis points a week ago; SoftBank's five-year CDS spread widened by 24 basis points to 424 basis points in one day. Meanwhile, the CDS spreads for NVIDIA, STMicroelectronics, and SpaceX also rose significantly.
According to data from LSEG and S&P Global Market Intelligence, the CDS spreads for Amazon, Alphabet, and Meta also rose to historic highs, although the overall rate of increase was slower than that of Oracle and CoreWeave. The credit insurance costs for these tech giants are also affected by the reassessment of financing risks for AI investments.
The CDS spread measures the cost that investors need to pay to hedge against debt default risk. A widening spread indicates that the market demands higher risk compensation, but it does not mean that a company is about to default, nor can different companies' CDS spreads be directly interpreted as comparable default probabilities.
The rising credit insurance costs for several AI-related companies reflect that investors are re-evaluating the financing methods for AI infrastructure investments. The large borrowing needs of companies like Oracle are under scrutiny, while CoreWeave, burdened with heavy debt, still unprofitable, and highly reliant on external financing, has become the focal point of market pressure.
Reuters pointed out that higher-than-expected U.S. inflation data and rising market concerns about future interest rate trends have intensified investor doubts about the return cycles of massive capital expenditures in AI. As the industry increasingly relies on debt rather than free cash flow to finance AI construction, the market's focus is shifting from the growth of computing power demand itself to whether related companies can timely generate sufficient profits and cash flow to cover the increasing interest expenses.
Approximately $50 Billion in Debt Looms, CoreWeave's Expansion Model Under Scrutiny
The core issue facing CoreWeave is the balance between capital expenditure growth and cash flow, financing capacity.
Media reports indicate that this AI cloud computing company is burdened with nearly $50 billion in debt and is still in a loss-making state. The company relies on large-scale procurement of NVIDIA GPUs, building data centers, and expanding computing power capacity to meet customer demand, and such investments typically require substantial upfront funding before revenue gradually materializes.
CoreWeave has significantly increased capital expenditures to seize the rapidly growing AI computing power market. During periods of strong demand, debt-fueled expansion can help companies build infrastructure in advance and support investment plans with long-term customer contracts. However, the long construction cycles of data centers and high equipment investments mean that if financing costs rise, projects are delayed, or customer demand grows less than expected, companies may face funding gaps and repayment pressures.
Thus, CoreWeave's problem is not just the high level of debt, but the market is questioning whether its future cash flow can cover capital expenditures, interest expenses, and other operating costs. Rising bond yields will further raise the threshold for new financing, making this issue even more prominent.
CoreWeave's management emphasizes that order reserves are sufficient and believes that the market has misjudged its financial situation. However, order reserves do not equate to cash already received: long-term contracts can provide some revenue visibility but do not automatically eliminate risks such as cost overruns, delivery delays, changes in financing conditions, and customer concentration. Investors need to assess whether these contracts can ultimately convert into sufficient cash flow and sustainable profits.
Why NVIDIA Stepped In to "Extinguish the Fire," Intertwining Supplier Financing and Customer Demand
Jensen Huang publicly expressed confidence in CoreWeave, reflecting the close business and capital ties between NVIDIA and this AI cloud service provider.
NVIDIA holds about 10% of CoreWeave's shares, making it its second-largest shareholder. At the same time, CoreWeave is also a significant purchaser of NVIDIA GPUs, with its business model relying on procuring NVIDIA chips, building data centers, and leasing computing power to AI developers and large tech companies.
If CoreWeave faces financing obstacles, subsequent data center construction, GPU procurement, and computing power delivery may be affected. Even if existing orders are not immediately canceled, rising financing costs may alter project construction rhythms and capital return expectations, thereby impacting market judgments about the growth of NVIDIA's AI demand.
A more sensitive issue is that arrangements where suppliers invest in customers and customers purchase supplier products can easily trigger market concerns about "circular financing."
Such transactions do not inherently imply wrongdoing, but when companies rely on borrowing to purchase products from suppliers, and suppliers hold equity in the companies, investors will question: how much of the growth in the supply chain comes from genuine demand from end customers, and how much relies on financing-driven continuous expansion?
Huang emphasized that CoreWeave's financing costs are decreasing and clearly stated that NVIDIA does not need to backstop it, which serves to maintain market confidence in an important partner while avoiding the market interpreting the business relationship between the two as NVIDIA having to bear CoreWeave's debt risk.
However, this statement cannot replace scrutiny of CoreWeave's balance sheet. NVIDIA's equity holdings do not equate to guaranteeing its debt, and Huang's optimistic assessment cannot directly resolve the company's financing needs, interest burdens, and cash flow issues.
Can AI Investment Returns Cover Massive Capital Expenditures? This Becomes the Core Market Issue
CoreWeave's credit turmoil is becoming a stress test for AI infrastructure investment.
Against the backdrop of rapidly growing demand for generative AI, tech companies and computing power operators are aggressively building data centers to capture future markets. However, infrastructure investments often precede revenue realization, especially for new cloud service providers relying on external financing, which need to continuously borrow to purchase GPUs, build facilities, and pay energy and operating costs.
When interest rate expectations rise and bond investors demand higher risk compensation, this model will face stricter scrutiny. Increased financing costs not only compress profits but may also force companies to slow down expansion; if expansion slows, it may impact future revenue growth and returns on existing investments.
Deutsche Bank strategist Jim Reid pointed out that this is not the first time significant market turbulence has occurred due to concerns about AI, but as the capital expenditure cycle for AI increasingly relies on debt rather than free cash flow, investors must pay more attention to the price signals in the credit market. "Overall, the financing costs related to AI are not yet high, but there are worrying signs emerging in some marginal areas."
This assessment highlights the key contradiction facing the industry: growth in computing power demand does not automatically equate to computing power operators being able to achieve sufficient profits; growth in orders does not necessarily mean that debt can be easily repaid.
For CoreWeave, the real test is whether it can control debt growth, continue to secure financing, and convert its large order backlog into sustainable operating cash flow. For NVIDIA and the entire AI industry chain, the market's focus is shifting from "how much computing power is still needed" to "who will pay for the construction of computing power, and whether these investments can ultimately generate sufficient returns."
Jensen Huang is trying to reassure the market, but the high bond yields for CoreWeave, record credit insurance rates, and widening CDS spreads for companies like Oracle and SoftBank indicate that investors are deeply scrutinizing the AI financing model. In the future, the valuation of the AI industry chain will not only depend on whether the demand for computing power can continue to grow but will increasingly depend on whether companies can convert this capital expenditure race into real, sustainable cash flow at manageable financing costs.