
The U.S. Department of the Treasury has revised the guidelines for U.S. Treasury bond issuance, removing the word "at least," which may pave the way for a reduction in long-term government bonds by 2027
The U.S. Treasury Department quietly revised its bond issuance guidance, removing a key phrase, which opens the door to reducing long-term Treasury issuance starting in 2027. This is the latest action by Secretary Scott Bessent in a series of measures aimed at suppressing long-end yields.
On Wednesday, the Treasury announced in its quarterly refinancing statement that it would maintain the auction sizes for nominal coupon bonds and floating rate notes unchanged over the next several quarters, but removed the term "at least," which had been used since early 2024. This subtle wording change indicates that the Treasury has reserved the flexibility to potentially reduce the issuance size of long-term bonds as early as 2027.
In terms of market impact, this move is one of a series of actions that Bessent has been pursuing over the past few months. Just two weeks after the August refinancing statement was released, the Treasury unexpectedly expanded the scale of Treasury buybacks significantly, but this measure failed to curb the rise in long-end yields, with the 30-year U.S. Treasury yield reaching its highest level since 2002 last month.
Traders had significant differences in their expectations regarding the changes that Wednesday's statement would bring, with some institutions believing that the guidance change would be limited given that yields had already retreated from their early October highs.
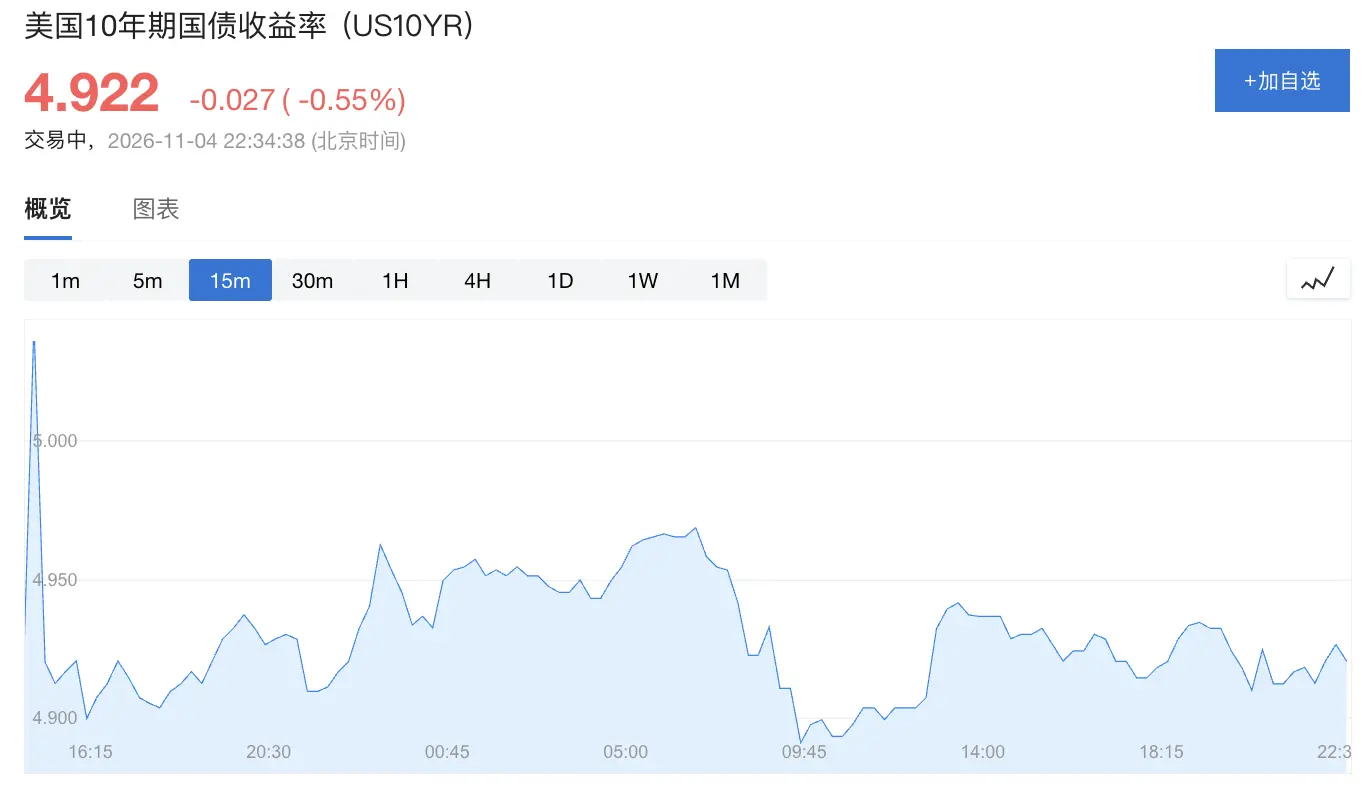
On Wednesday, the 10-year U.S. Treasury yield fell by 3 basis points to 4.922%.
Change in Wording: Removal of "At Least"
This wording adjustment may seem minor, but it is significant.
Since early 2024, the Treasury has stated that the auction size for coupon bonds would "remain unchanged at least for the next several quarters," a statement that the market widely interpreted as excluding the possibility of a near-term reduction in supply. By removing "at least," the Treasury has effectively retained the flexibility to adjust at any time.
As early as February 2025, the Treasury Borrowing Advisory Committee (TBAC)—a consultative group composed of bond investors, dealers, and other market participants—had recommended that the Treasury remove or modify its forward guidance.
In August of this year, the TBAC again urged the Treasury to "consider updating the forward guidance language to retain operational flexibility before the fiscal year 2027."
On Wednesday, the TBAC formally recommended that the Treasury modify the forward guidance language and "emphasized that clear communication and a regularly predictable operational framework are crucial for helping market participants adapt to future changes."
Notably, in the previous refinancing statement on August 5, the Treasury had already made a preparatory adjustment, changing the assessment wording for adjustments to coupon bonds and floating rate notes from "increases" to "changes," leaving a hint for future supply reductions. The removal of "at least" further clarifies this signal.
Buyback Operations: Scale Maintained at Three Times Level
Regarding bond buybacks, the Treasury stated on Wednesday that the upcoming long-term Treasury buyback operations would have a maximum purchase limit of $6 billion per transaction, consistent with recent practices. This scale had already been three times the previous limit.
The Treasury also indicated that it would "continue to assess the room for improvement in buyback operations, including adjustments to the maximum purchase limit, scheduling and frequency of buyback operations, bond eligibility criteria, and execution processes," suggesting that there may be further expansions of operations in the future.
However, the expansion of buyback scale has not achieved the expected effect of lowering long-end yields. The 30-year U.S. Treasury yield still climbed to a high level last month, indicating that the market's response to this series of Treasury actions has been relatively limited.
Supply-Demand Imbalance: Weakening Demand for Long-Term Assets from Fixed Income and Pension Funds
In this quarter's refinancing, the total amount for next week's auctions remains at $125 billion, unchanged for the 11th consecutive time, with specific components being: $58 billion in 3-year Treasury notes on November 9, $42 billion in 10-year Treasury notes on November 10, and $25 billion in 30-year Treasury notes on November 12.
A deeper issue lies in the fiscal deficit. The U.S. government's annual fiscal deficit is approximately $2 trillion, leading to a sustained increase in demand for Treasury issuance.
As a result, the Treasury is increasingly relying on short-term Treasury bills with maturities of no more than one year. However, the current proportion of short-term Treasury bills to total outstanding debt has exceeded historical normal levels, and as short-term bonds must be refinanced at prevailing market rates, the sensitivity of national debt repayment costs to interest rate shocks is rising.
Meanwhile, the Federal Reserve recently resumed interest rate hikes for the first time since 2023, with investors expecting further actions in the coming months.
On the long-term demand side, both officials and market participants have noted that institutional investors, such as fixed income pension funds, have shown a continued weakening demand for long-term assets in recent years.
In preparing this statement, the Treasury systematically assessed the supply-demand dynamics of long-end bonds by conducting routine surveys of primary dealers regarding the "structural changes" in Treasury investor demand and "how future auction sizes should be adjusted."
Since the establishment of the current forward guidance framework by Bessent's predecessor Janet Yellen, traders have generally expected that the supply of coupon bonds would eventually resume growth. This revision of guidance marks a fundamental shift in that expectation, indicating that the framework for communication between the Treasury and the market is entering a new phase.
Risk Warning and Disclaimer
The market carries risks, and investments should be made cautiously. This article does not constitute personal investment advice and does not consider individual users' specific investment goals, financial situations, or needs. Users should consider whether any opinions, views, or conclusions in this article align with their specific circumstances. Investing based on this is at one's own risk.