
Is the U.S. stock market weakening the cryptocurrency market cycle?
Author: Zhou, ChainCatcher
On October 15, OKX and ICE's joint venture tokenized stock platform OKXICE announced that among the 63 U.S. stocks it plans to launch, nine listed companies, including Verizon, Broadcom, and UnitedHealth, have opposed based on the SEC's new regulations, and the related stocks will not be tradable on the platform.
At the same time, Nasdaq also stated that it would not allow its own stocks to be tokenized under this framework.
This is the first time since the SEC introduced the innovative exemption in September that listed companies have collectively exercised their veto rights. What does tokenization mean for U.S. stocks and the crypto market?
1. The Costs of Tokenizing U.S. Stocks Are Becoming Apparent
According to the innovative exemption released by the SEC on September 17, on-chain tokenized securities trading venues do not need to register as exchanges to trade already issued U.S. stocks. Third-party tokenization does not require prior consent from the listed companies but must provide written notice in advance. If the listed companies raise objections within 30 days, the stocks cannot be traded at that venue.
OKXICE is the first venue to issue an opening announcement based on this rule. According to its announcement, the platform is deployed on X Layer, using a Uniswap v4 liquidity pool with access control, pairing stocks with stablecoins such as USDC, USDG, and USDT for round-the-clock trading. The price in the pool is determined solely by the ratio of the quantities of the two assets, without using an oracle, and there are no circuit breakers except for trading halts. The announcement also acknowledges that token prices may deviate from the underlying stocks, especially outside regular trading hours.
For listed companies, this means their stocks will enter a market where they cannot control pricing. Among the nine companies that raised objections, CoreWeave, AppLovin, and Applied Digital are popular AI and retail investor stocks, which are also the targets that crypto traders most want to trade.
Nasdaq's reasoning is more direct; it does not want its stocks traded in a venue that cannot display optimal prices in real-time and does not report transactions to a comprehensive market system. It is worth mentioning that Nasdaq itself is a competitor of ICE, the parent company of the New York Stock Exchange, which was approved by the SEC in March this year to trade stocks in a tokenized form.
Market views suggest that the bottleneck for Real World Assets (RWA) lies in authorization, specifically who is qualified to turn the economic rights of a stock into an on-chain token. The objections from these nine companies are precisely about this right.
Just last weekend, the market experienced a flash crash. Around 5:22 AM Beijing time on October 18, during the U.S. stock market's closure, the perpetual contracts for U.S. AI concept stocks on the crypto platform suddenly plummeted.
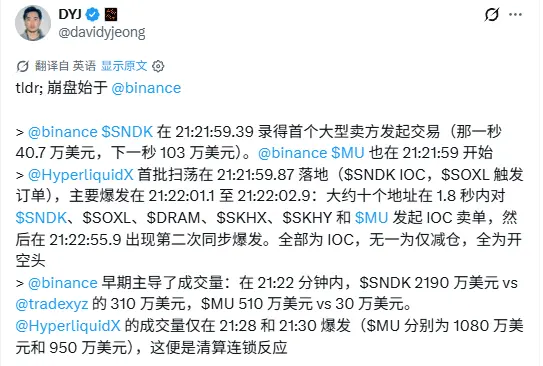
DYJ, CEO of trading execution platform Tread.fi, stated that the flash crash sell-off began at Binance, with the SNDK contract seeing large active sell orders first, with about $407,000 executed in one second, followed by about $1.03 million the next second. Less than a second later, there were sweep orders on Hyperliquid, with about 10 addresses concentrating on selling six contracts, including SNDK, MU, and SOXL, all opening new short positions. About six minutes later, the trading volume of the MU contract on Hyperliquid surged to about $10 million per minute, which DYJ attributed to chain liquidation.
The MU contract on Binance once dropped to $818.57, down about 6% from before the flash crash, but subsequently recovered most of the losses within an hour.
Real shareholders' accounts were unaffected over the weekend; it was those using leverage to trade these contracts that were liquidated. Although prices have returned, their positions have exited.
The weekend itself is the weakest period for tokenized U.S. stocks. According to a post by Decentralisedco comparing data from 30 weekends since March, it was found that when the opening gap on Monday exceeds 1%, the accuracy of predicting the direction of perpetual contracts is 69%, but by Sunday night New York time, it only reflected about a quarter of the gap magnitude.
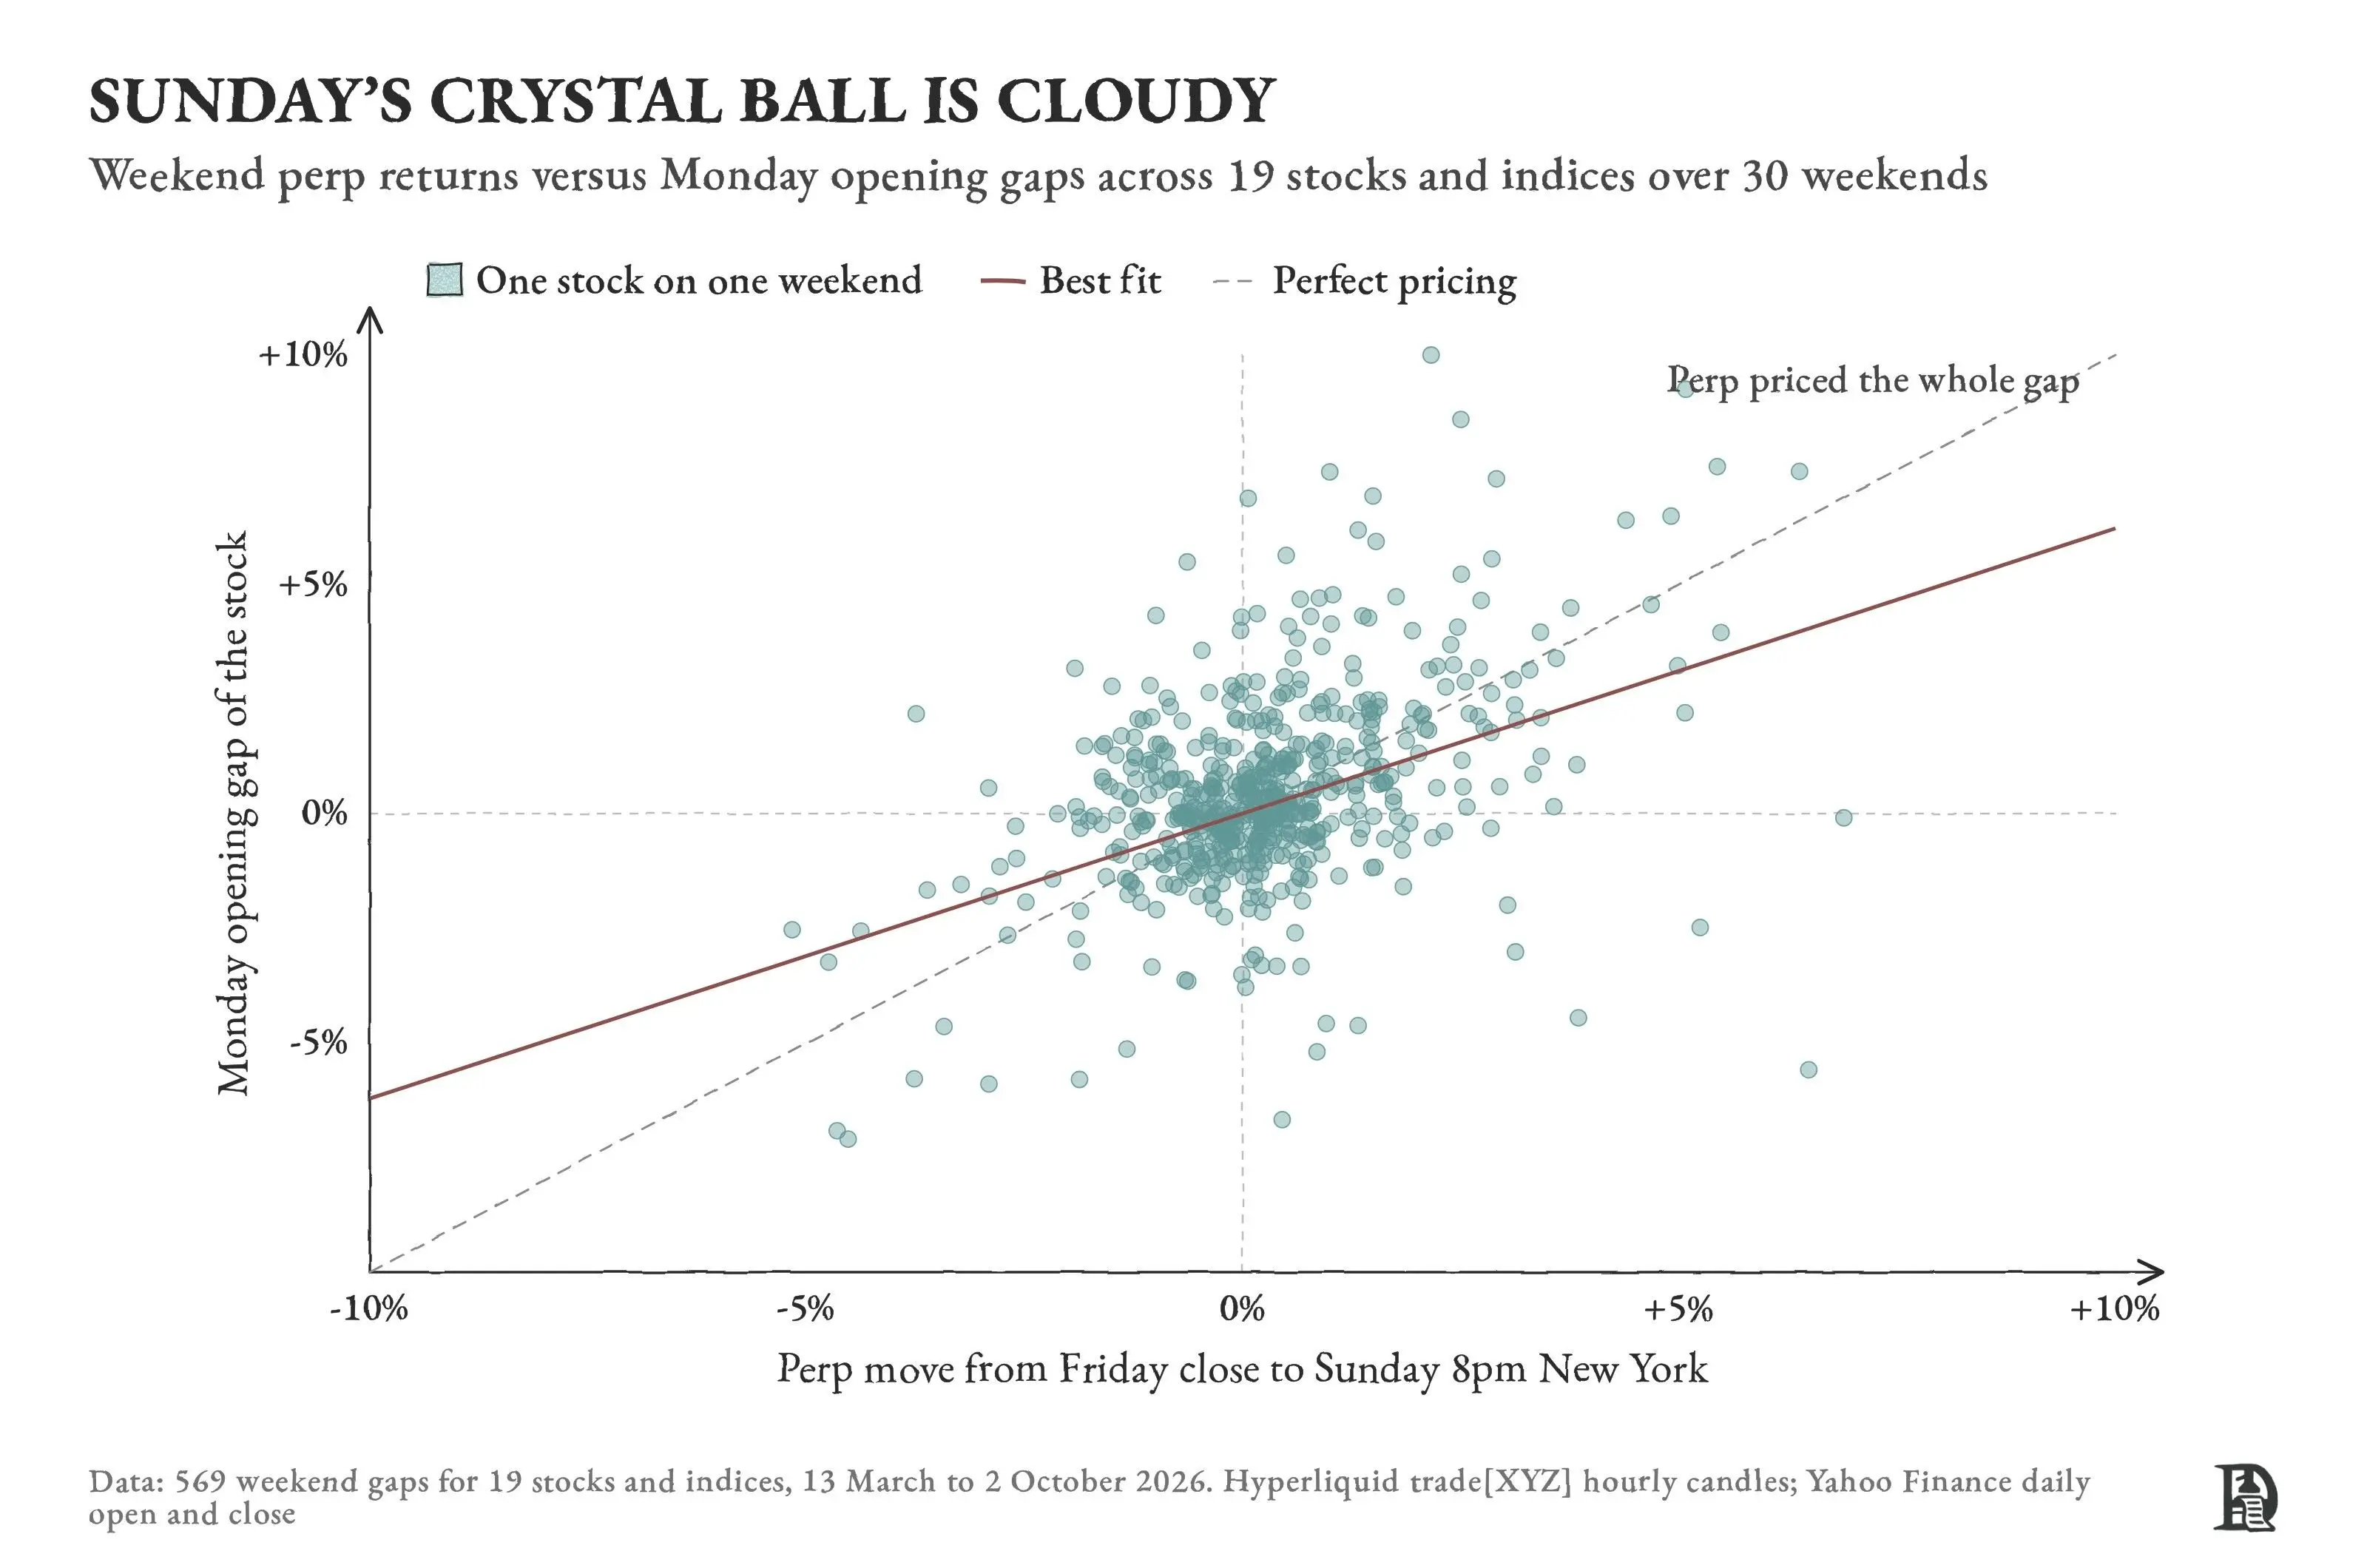
Thin trading, inaccurate pricing, and the leverage and liquidation mechanisms can amplify shocks. The IMF pointed out in its October Global Financial Stability Report that the volatility of tokenized stocks is about 1.5 times that of the corresponding stocks. IMF financial advisor Tobias Adrian believes that the inefficiencies that tokenization attempts to eliminate serve as shock absorbers in traditional markets. The weekend market closure is precisely such a buffer.
2. Is the U.S. Stock Market Weakening the Crypto Market Cycle?
Over the past decade, Bitcoin's price has generally followed a four-year cycle formed by halving. In previous bear markets, Bitcoin's decline from its peak has ranged from 77% to 93%.
The cost of a bear market is not only reflected in price; a large amount of capital exits the market, and the industry often has to wait for the next bull market to re-gather funds and popularity.
The rhythm of this round has not changed; Bitcoin is expected to peak at about $126,000 in October 2025, approximately 540 days after the halving in April 2024, consistent with historical patterns. However, the amplitude has noticeably decreased. On June 5 of this year, Bitcoin fell to about $59,100, a retracement of about 53%, and has gradually rebounded, recently returning to around $85,000.
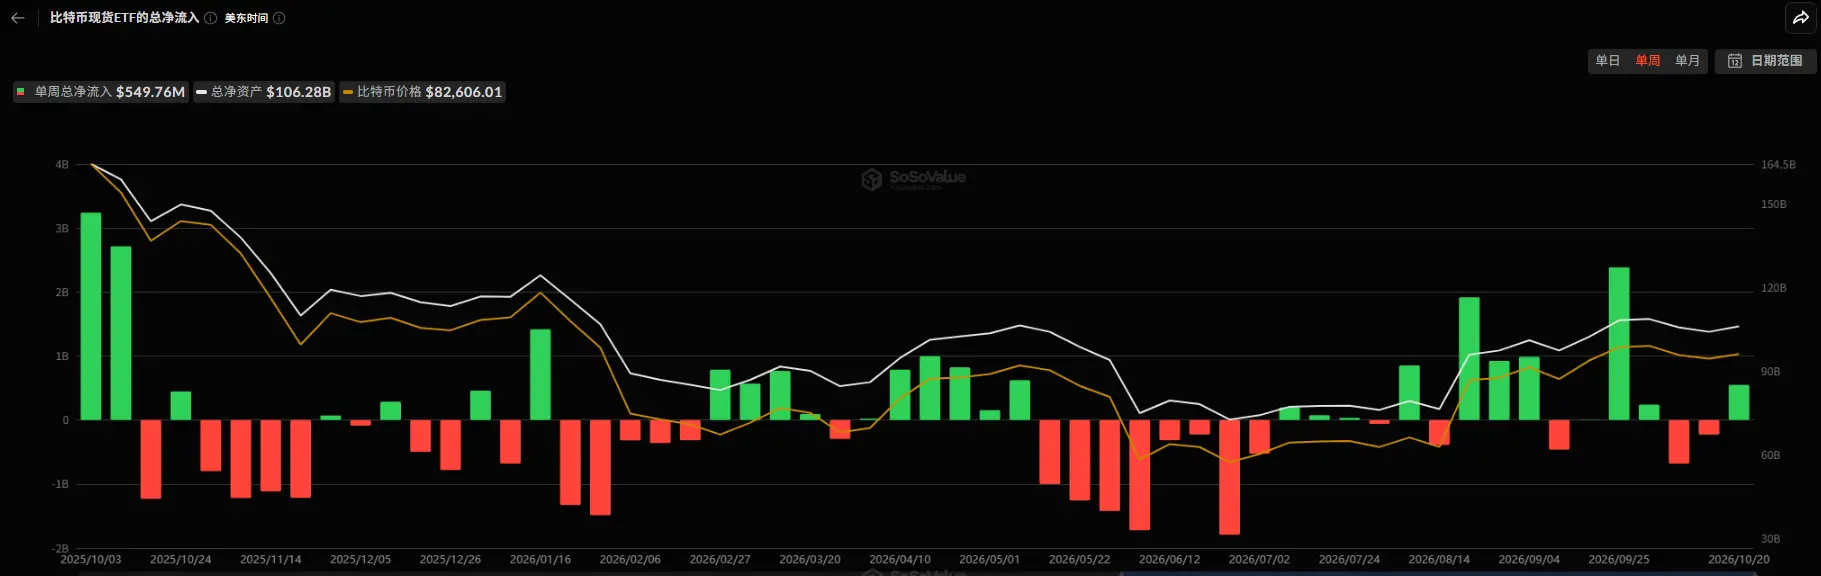
The shallower decline first depends on who is supporting the bottom. Regarding Bitcoin spot ETFs, according to SosoValue data, from November 2025 to June 2026, the total net outflow from ETFs was about $10 billion, with about $4.5 billion flowing out in June when Bitcoin bottomed, and from July to September, there was a total net inflow of about $6.3 billion.
In terms of Bitcoin treasury companies, according to statistics from BitcoinTreasuries.net, the selling volume of listed treasury companies exceeded the buying volume in February this year, with almost only Strategy continuing to buy. According to its filings with the SEC, Strategy's Bitcoin holdings increased from about 650,000 coins at the end of November 2025 to 843,775 coins in late June 2026, an increase of about 194,000 coins. In January of this year, Strategy accounted for 97.5% of the net increase in holdings among listed companies. However, Strategy paused its buying after the week of June 22 and began accumulating dollar reserves instead.
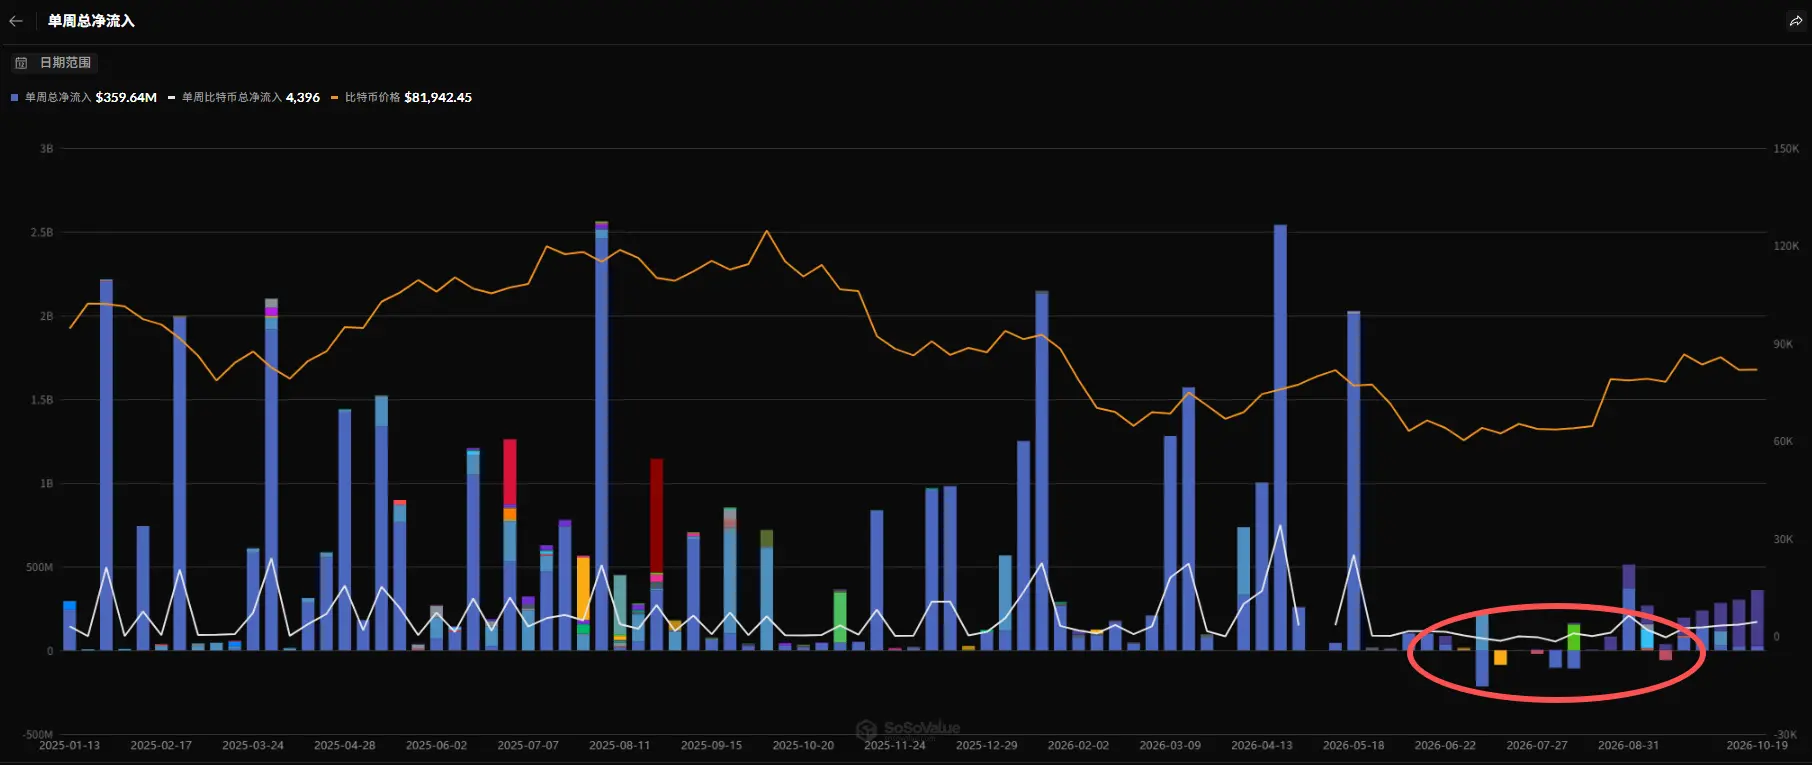
In other words, the support for the price level in this bear market largely relies on the financing ability of a single company.
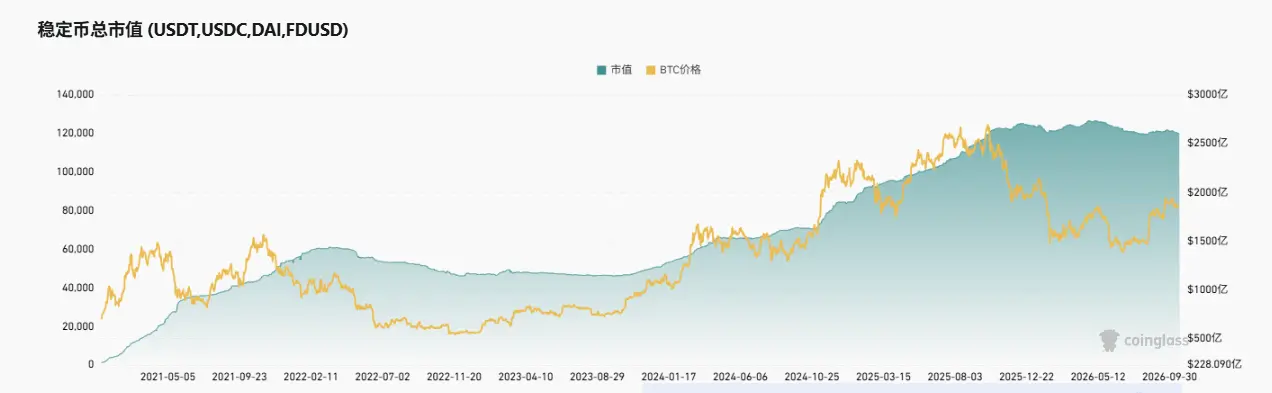
At the same time, another change is occurring on-chain—stablecoins have not exited the market in large quantities as they did in the previous round. CoinGlass data shows that after Bitcoin peaked in October 2025, the market cap of USDT continued to grow, peaking around April and May this year, and has since stabilized at about $183 billion, while USDC has only slightly retreated.
Statistics show that the contraction of stablecoins from their peak this year is about 3%, far lower than the 26% decline in 2022. Of course, part of the shrinkage in 2022 was due to the collapse of Terra and the Silicon Valley Bank incident.
In addition, on-chain funds have found new places to stay. According to RWA.xyz data, the scale of tokenized U.S. Treasury bonds has increased from about $9 billion in October 2025 to a peak of about $16 billion in mid-2023, and has started to decline after Bitcoin's rebound, currently around $14.5 billion.
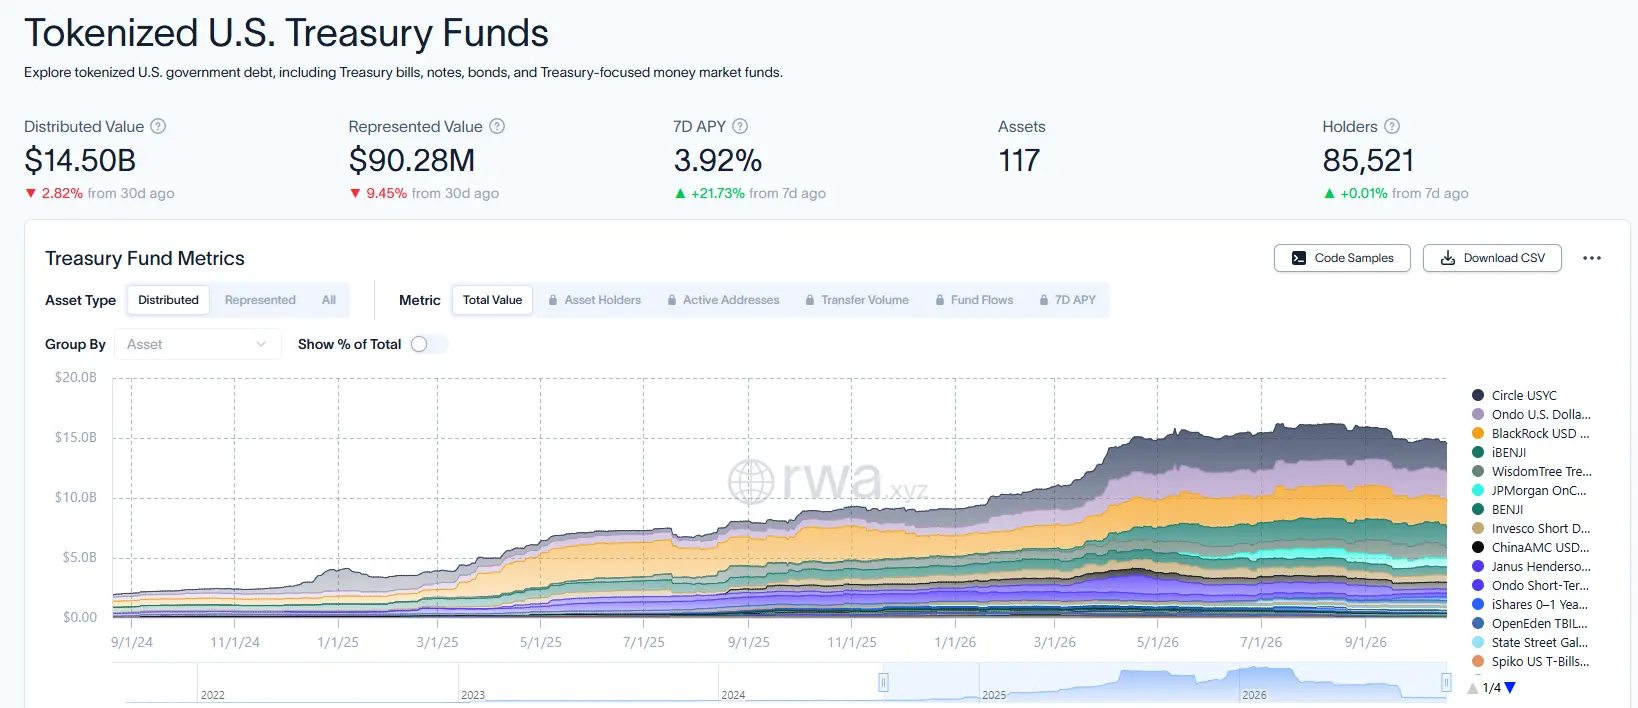
The holders of tokenized Treasury bonds number about 85,500, mainly institutions and DeFi protocols, and the scale is much smaller than Strategy's purchases, but there was almost no such outlet in the previous bear market.
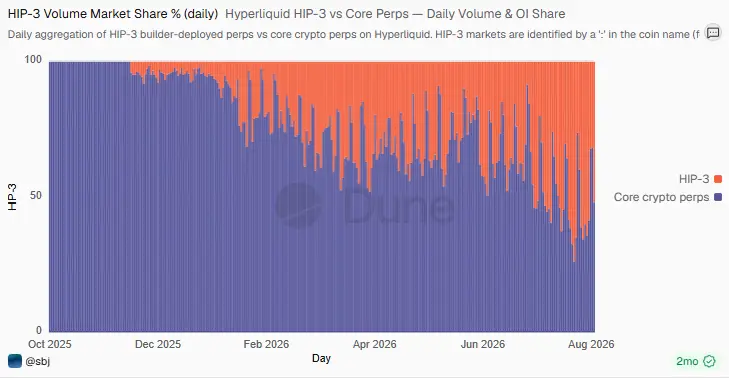
On the other hand, the revenue structure of exchanges is also changing. According to Dune data dashboards, by mid-December 2025, the HIP-3 market on Hyperliquid, primarily consisting of stocks, indices, and commodities, accounted for only 4% of daily trading volume. By this summer, the proportion had reached four to six times on most trading days, peaking at 74% on July 30.
This includes factors related to the shrinking trading of crypto assets, but during the crypto market downturn, exchanges have indeed developed businesses that do not rely on coin prices.
Crypto researcher Haotian believes that the crypto industry is shifting from a bull market in asset issuance to a bull market in the distribution of global assets on-chain. In other words, in the next bull market, some incremental funds will flow into tokenized U.S. stocks, which may flatten the peak of the bull market.
At the same time, the impact of halving itself is diminishing. Currently, the Bitcoin block reward is 3.125 coins, which will drop to 1.5625 coins in 2028. When traders on crypto platforms are simultaneously focused on earnings season and the Federal Reserve's interest rate decisions, the crypto market cycle will more closely follow the rhythm of global liquidity and the U.S. stock market.
3. The Crypto Market Needs U.S. Stocks Far More Than U.S. Stocks Need Crypto
For companies like Broadcom and Verizon, being tokenized offers almost no benefits; they neither lack liquidity nor financing channels. According to CoinFound, the trading volume of overseas tokenized stocks compared to traditional market trading volume has a median of only 0.084% for 49 stocks.
Although Wall Street is also promoting tokenization, they are taking a different path. In December 2025, DTC received a no-objection letter from the SEC, allowing it to convert the securities it custodies into on-chain tokens, covering Russell 1000 component stocks, which account for about 95% of the investable market cap of U.S. stocks. In Nasdaq, tokenized shares and traditional shares are matched on the same order book, with the only difference being the delivery method after the transaction.
This route does not rely on stablecoins, and tokens can only be transferred between wallets registered with DTC. Michael Winnike, the strategic head of DTCC, believes that tokenization should transform market functions while retaining the security guarantees that existing markets rely on.
Conversely, crypto funds cannot support the tokenization market for U.S. stocks. Decentralisedco estimates that foreign investors hold approximately $19.86 trillion in U.S. stocks. Even if one-tenth of all stablecoins were to flow into stock tokens, it would only increase by about $31 billion, with the remaining increment needing to come from stocks already held in brokerage accounts.
What is more noteworthy is what crypto funds are buying. Data from RWA.xyz shows that as of October 19, the scale of on-chain tokenized stocks is approximately $3.45 billion. Among them, tokens related to Strategy total about $368 million, and those related to Circle are about $307 million, together accounting for approximately 19.6%, which is 2.6 times the total of four broad-based index products.
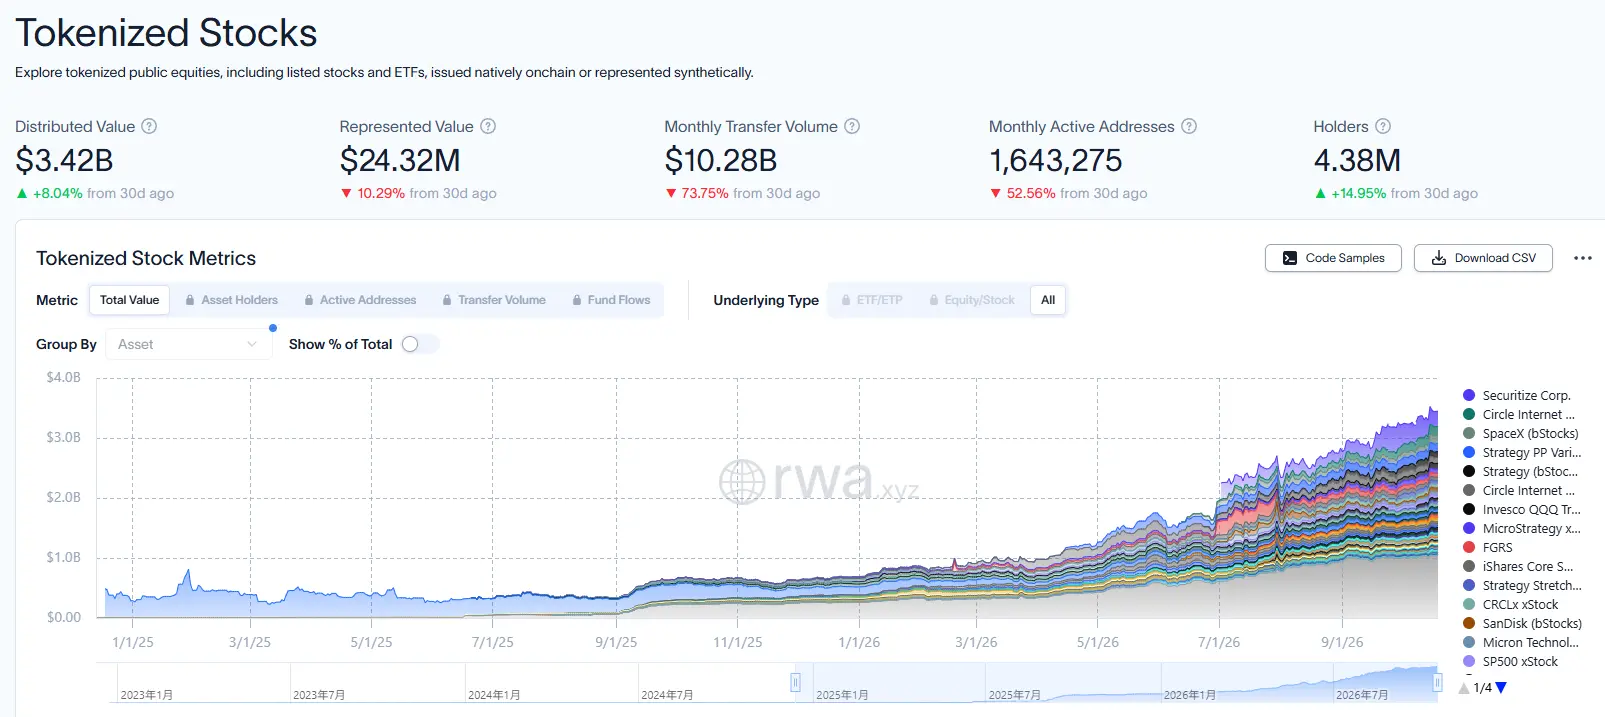
CoinFound indicates that the top three U.S. stocks purchased by crypto funds are Circle, Strategy, and Coinbase, which rise and fall in tandem with the crypto market, making such holdings difficult to diversify risk.
The forms that can stabilize are also the most tightly regulated. According to SEC rules, the tokenized trading volume of a single stock cannot exceed a certain percentage of the average daily trading volume from the previous month, with large-cap stocks at 0.25% and other stocks at 2.5%. Calculations show that the first batch of 63 stocks on OKXICE has a daily total limit of about $710 million, with Nvidia having a maximum of about $64 million per day. Coupled with the issuer's veto power, compliant routes are unlikely to scale up in the short term.
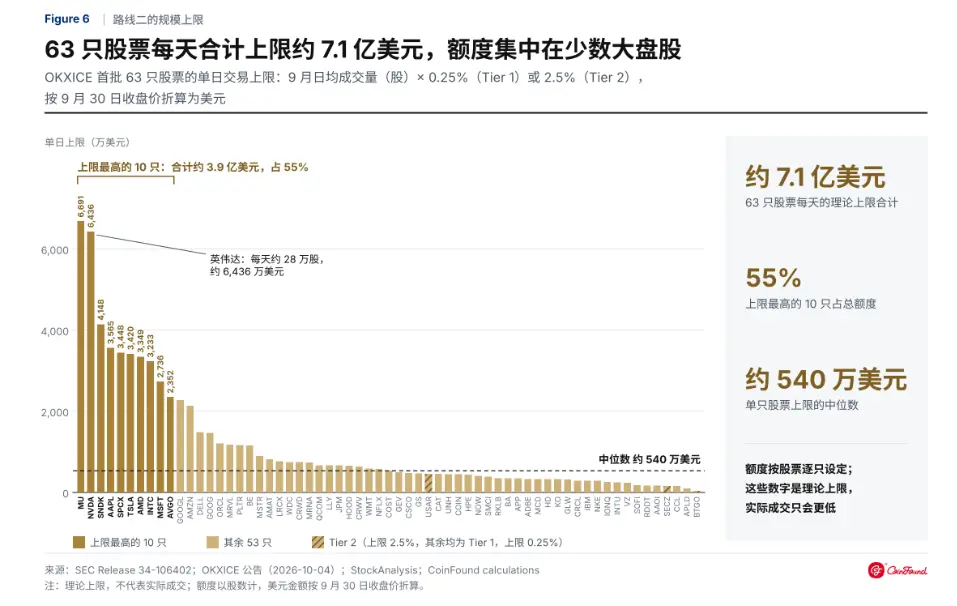
At the same time, the open interest of stocks, indices, and ETF perpetual contracts on tradeXYZ is about $3.01 billion, equivalent to 94% of the total value of all on-chain stock tokens. At the beginning of September, a memecoin liquidity pool on Robinhood Chain held 53% of all tokenized HIMS, and a buy order of about $39,000 pushed the token price to $132.64, while the New York closing price was only $28.84.
The crypto market needs U.S. stocks to smooth out cycles but can only obtain them according to Wall Street's rules, while the compliant forms that can stabilize are the most restricted. This may be the reason why tokenization of U.S. stocks sounds good but takes effect slowly.
Conclusion
For a long time, the root cause of the crypto market's boom and bust has been that the value of most assets comes from the market's expectations of crypto itself. Price increases attract funds, which in turn push prices higher, and the same happens during declines; the entire market lacks an anchor independent of its own emotions.
Tokenized U.S. stocks and government bonds provide just such an anchor. Their value comes from corporate profits and interest rate levels, with no necessary connection to coin prices. With such assets, funds can remain during bear markets, exchanges and protocols can rely on services to maintain operations, and developers have reasons to plan across cycles.
The premise is that the crypto industry is willing to accept the rules of traditional markets, allowing U.S. stocks to enter the chain in the form of collateral and places where funds reside. If it is only made into another high-leverage chip, it will only bring about more severe fluctuations.
This also means that native tokens will no longer monopolize on-chain capital. However, a crypto market that does not need to be rebuilt every four years may be the most profound significance of tokenization for this industry.